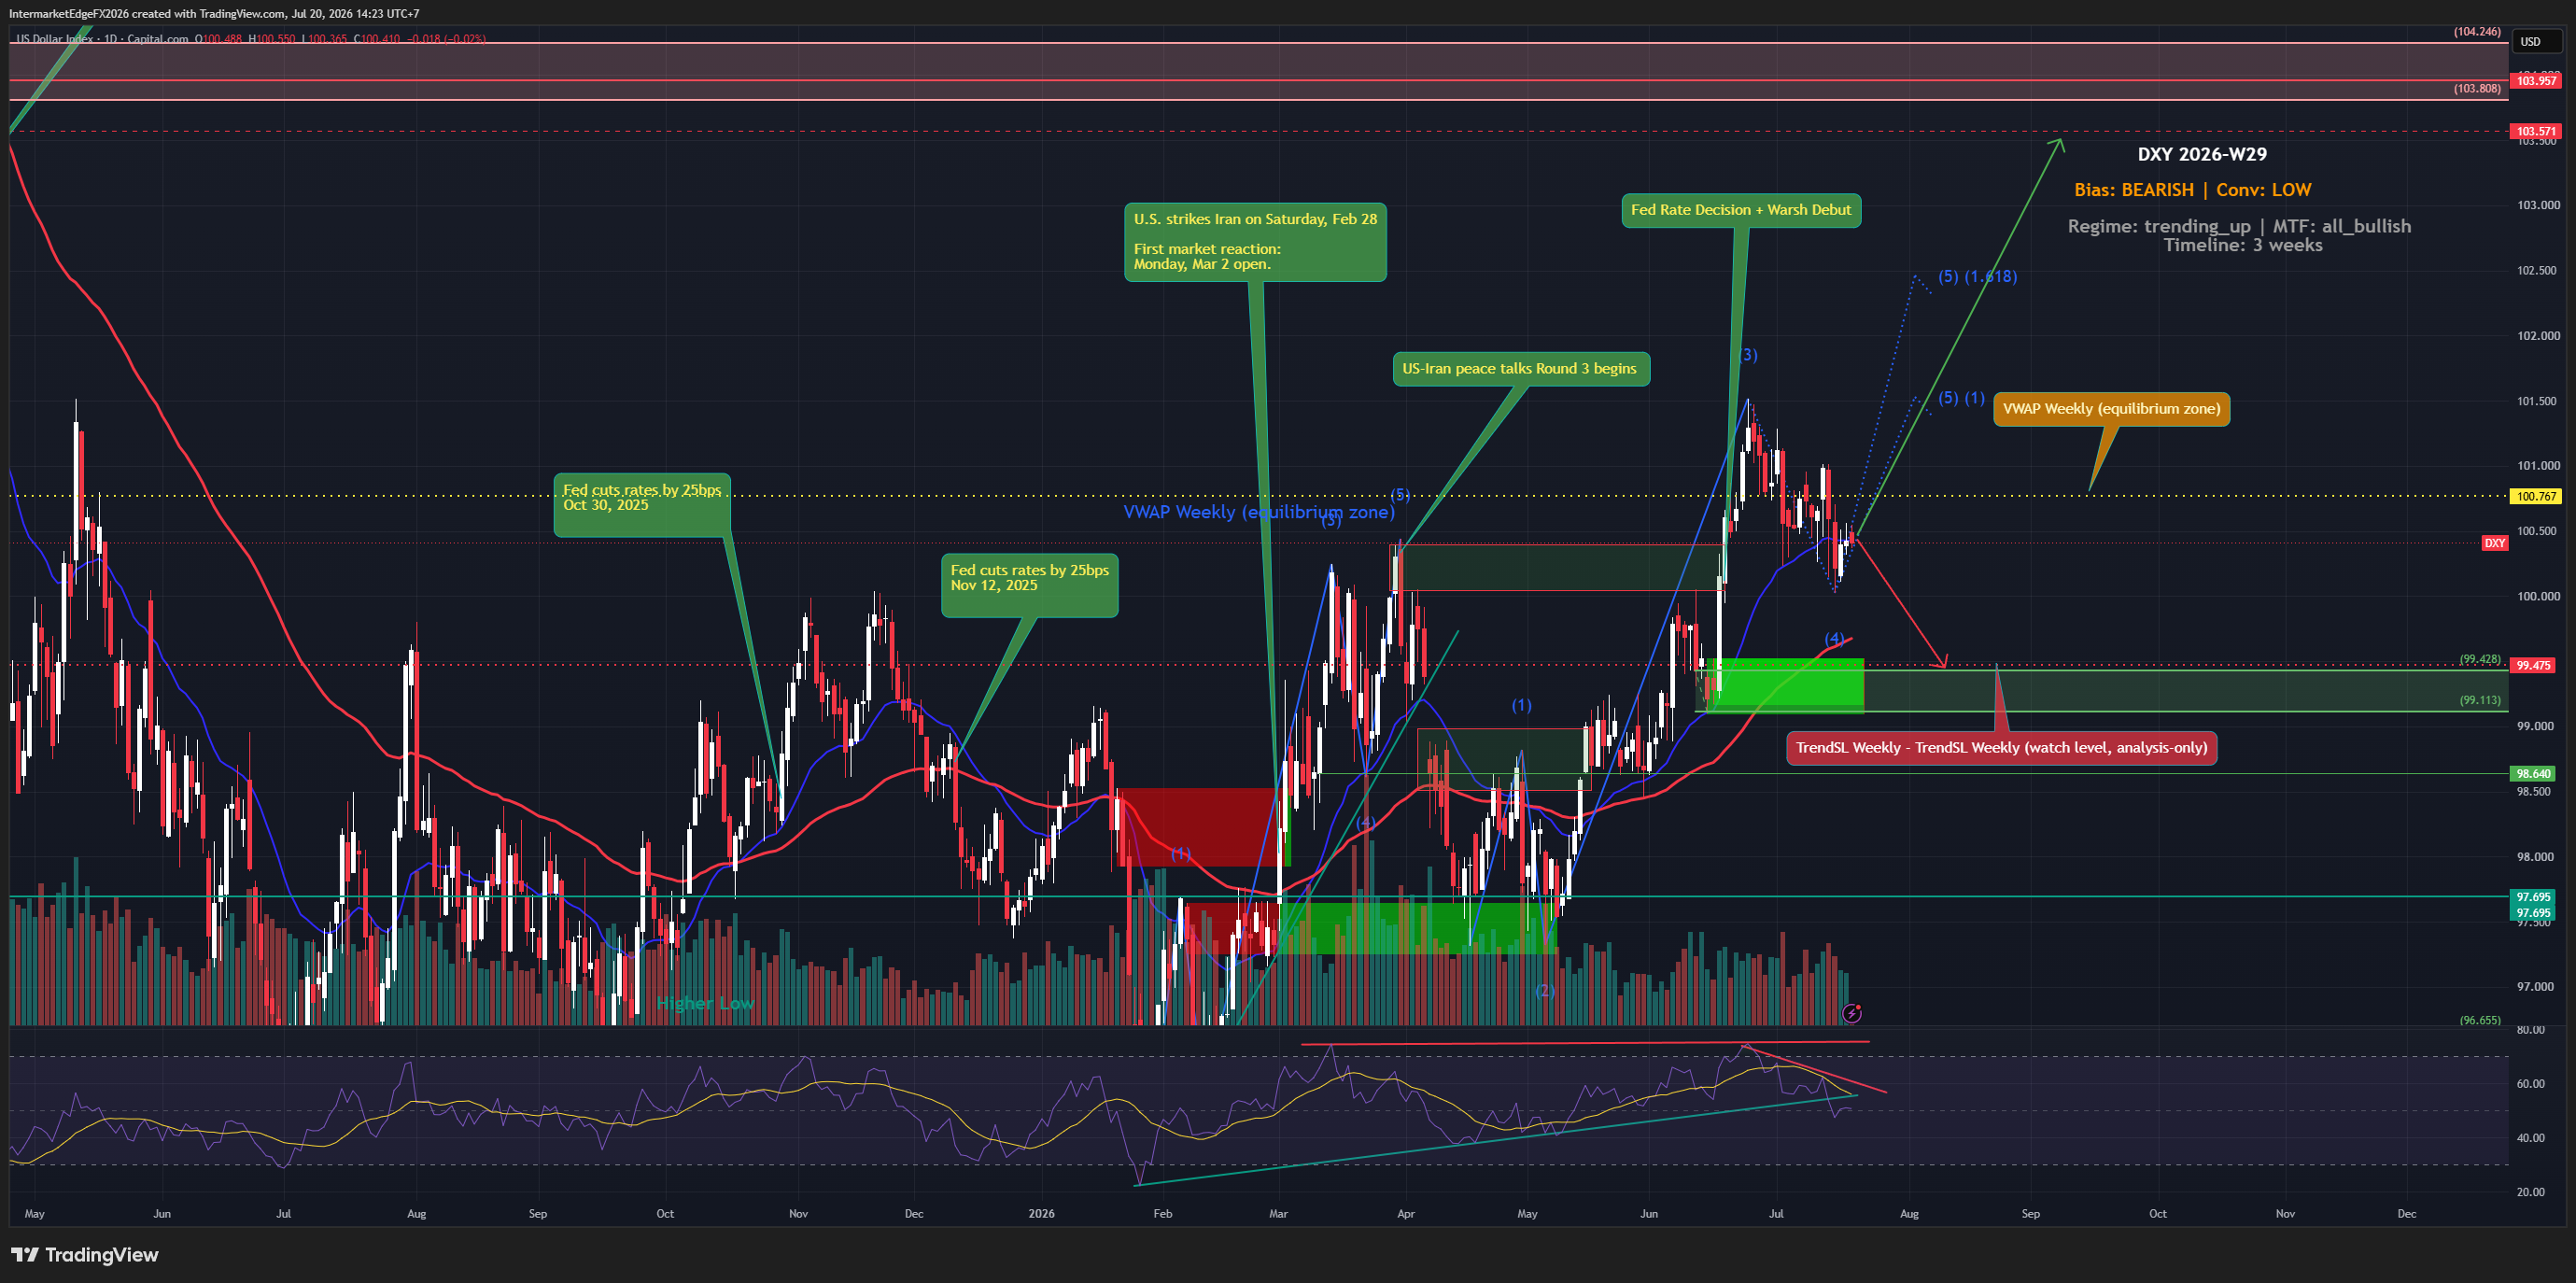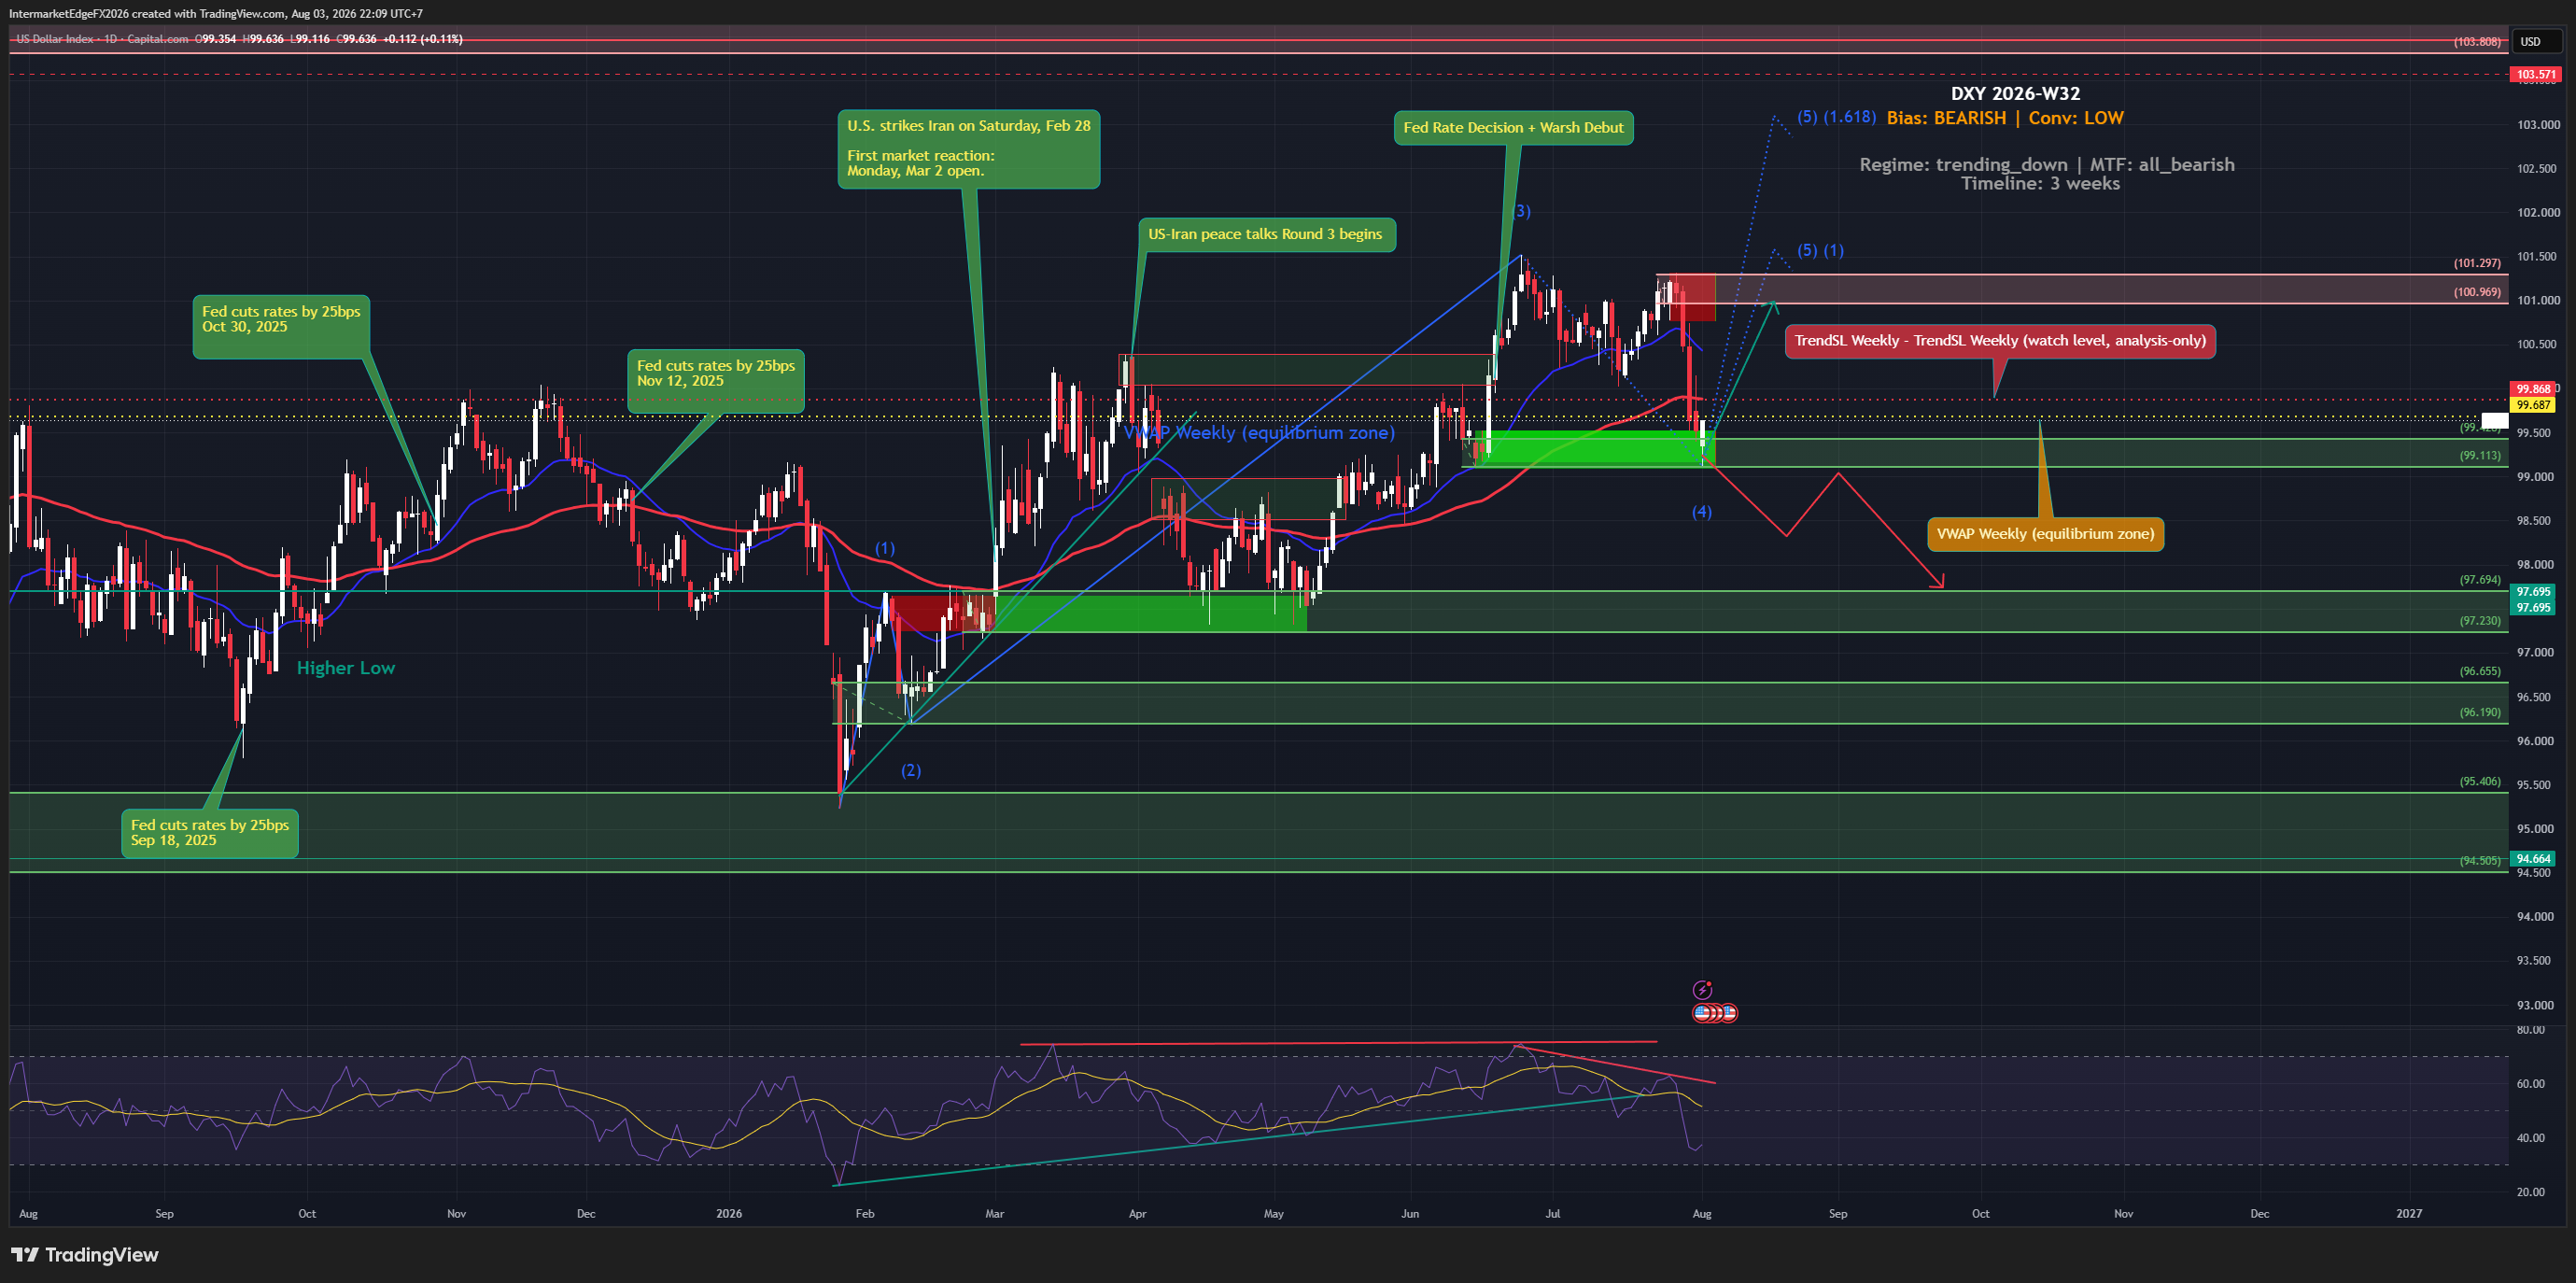
DXY Week W32-2026: ISM Manufacturing Surges to 55.6 as Dollar Tests VWAP at 99.687 From Above, But Macro Signal Conflict Keeps Bears Cautious
The US Dollar Index is under a trending bearish regime heading into Week W32-2026, yet the setup is anything but clean. Manufacturing activity just printed its strongest reading since May 2022, core CPI missed forecasts badly, and price is currently pressing against a critical structural level, all while the overall bias remains bearish with low conviction. This is a week for watching and assessing, not for forcing a position. The overall bias on DXY for Week W32-2026 is bearish, but conviction is explicitly low, and traders must handle this carefully. The multi-timeframe technical regime is aligned bearish across all timeframes, and the broader trend regime is classified as trending down with moderate confidence. That said, the signal picture is heavily conflicted. Both price action and the macro backdrop are currently pointing toward Dollar strength, the ISM beat, the still-elevated real yield of 2.41%, and the active causal chains around Fed policy relative to the G6 central bank basket and the residual influence of the prior hot inflation environment all argue for USD resilience. The rule engine's bearish override is driven by Fed policy divergence assessed relative to the broader G6 central bank basket, not by any single domestic data point, and it represents a structural thesis rather than a tactical one. Critically, three of five signal input categories, positioning data, liquidity indicators, and sentiment surveys, fired zero confirming signals this week. That is not a minor gap; it means the bearish call is resting on a much narrower evidential base than would normally justify an active directional stance. A macro bullish signal is also present but flagged as a provisional placeholder, subject to override if positioning data aligns in future reports. -- Intermarket Edge