Tag: Fed — InterMarketEdge

Tag: Fed

EURUSD Week W39-2026: Dollar Firms Toward a Ten-Week Low as the Fed-ECB Rate Gap Widens

EURUSD Week W39-2026: Dollar Firms Toward a Ten-Week Low as the Fed-ECB Rate Gap Widens

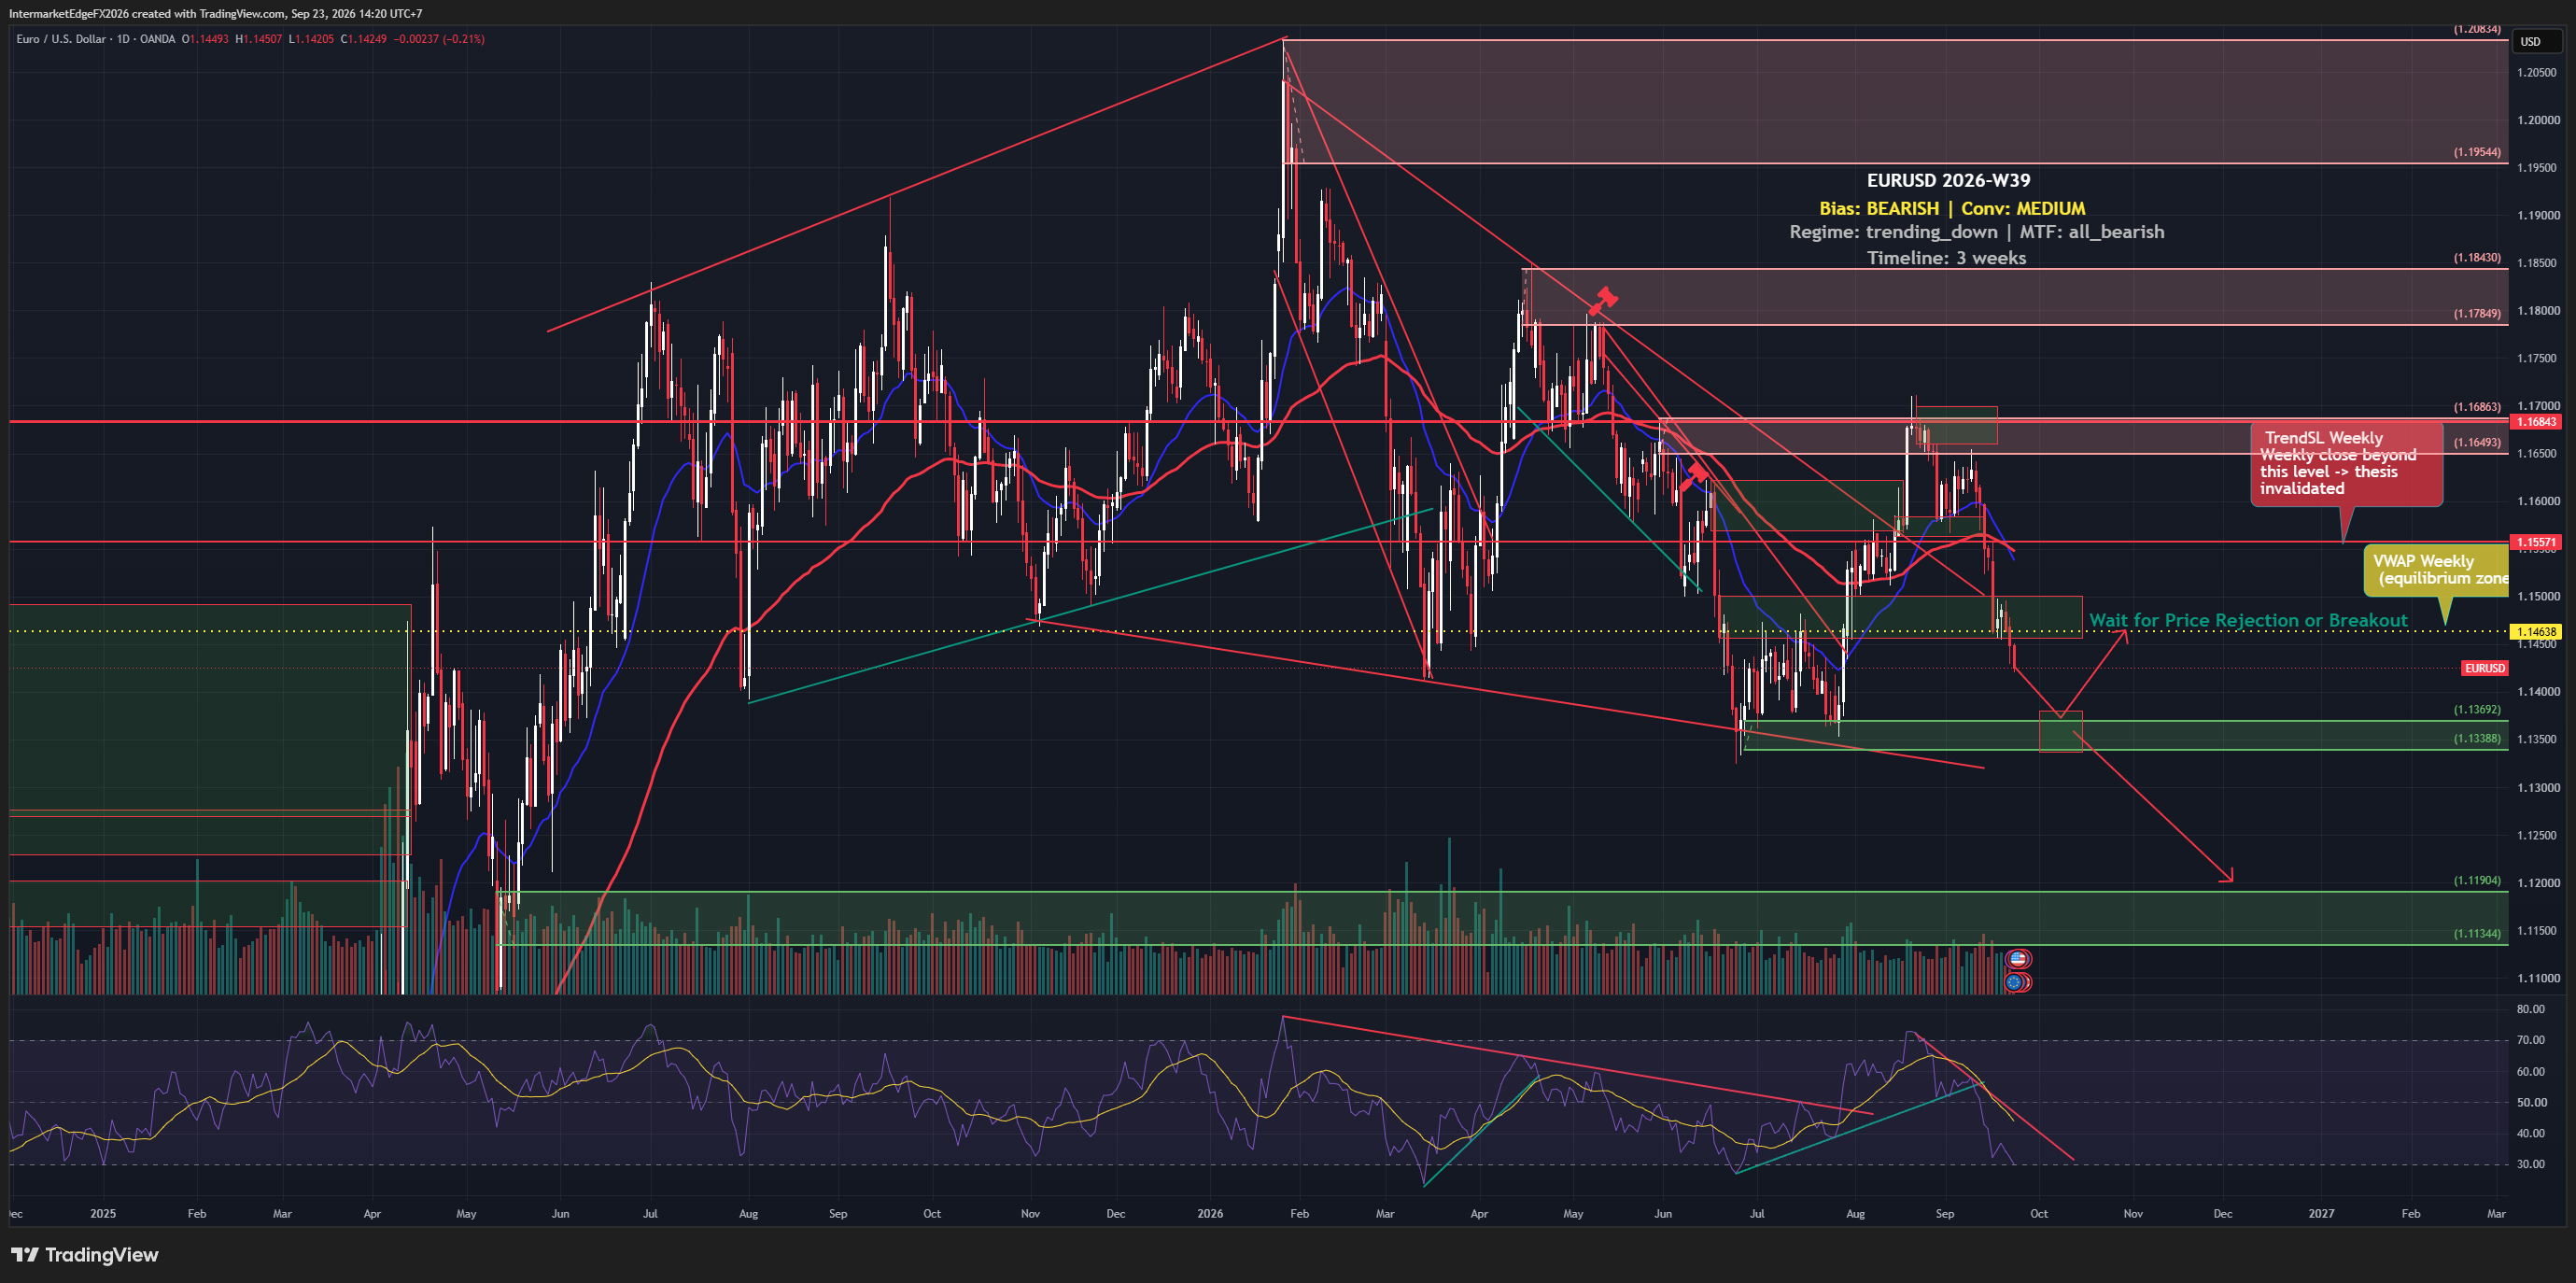
EURUSD is trading near a ten-week low, but the case is more specific than a simple strong-dollar story. At the Wednesday, 23 September 2026 observation, price was 1.14263, below weekly VWAP at 1.14638 and weekly TrendSL at 1.15571. The Fed's hawkish optionality and a US 10-year real yield of 2.62% leave the relative rate backdrop more supportive of the dollar, even after the ECB's September rate increase. Oil weakness could reduce part of the energy-inflation pressure behind the ECB's move, although that effect remains a scenario rather than a known policy outcome. DXY and short-term technical signals do not offer perfect confirmation, so conviction remains medium. FXSSI reports 66% of its broker-level sample net long EURUSD; that is contrarian context only. A sustained move above 1.14638 would warn that short-term momentum is turning against the thesis. A weekly close above 1.15571 would invalidate the bearish structure. The decision framework favors patience rather than chasing weakness near the recent low.
GBPUSD Week W38-2026: Yield Pushes Toward 5% but the Dollar Refuses to Confirm

GBPUSD Week W38-2026: Yield Pushes Toward 5% but the Dollar Refuses to Confirm

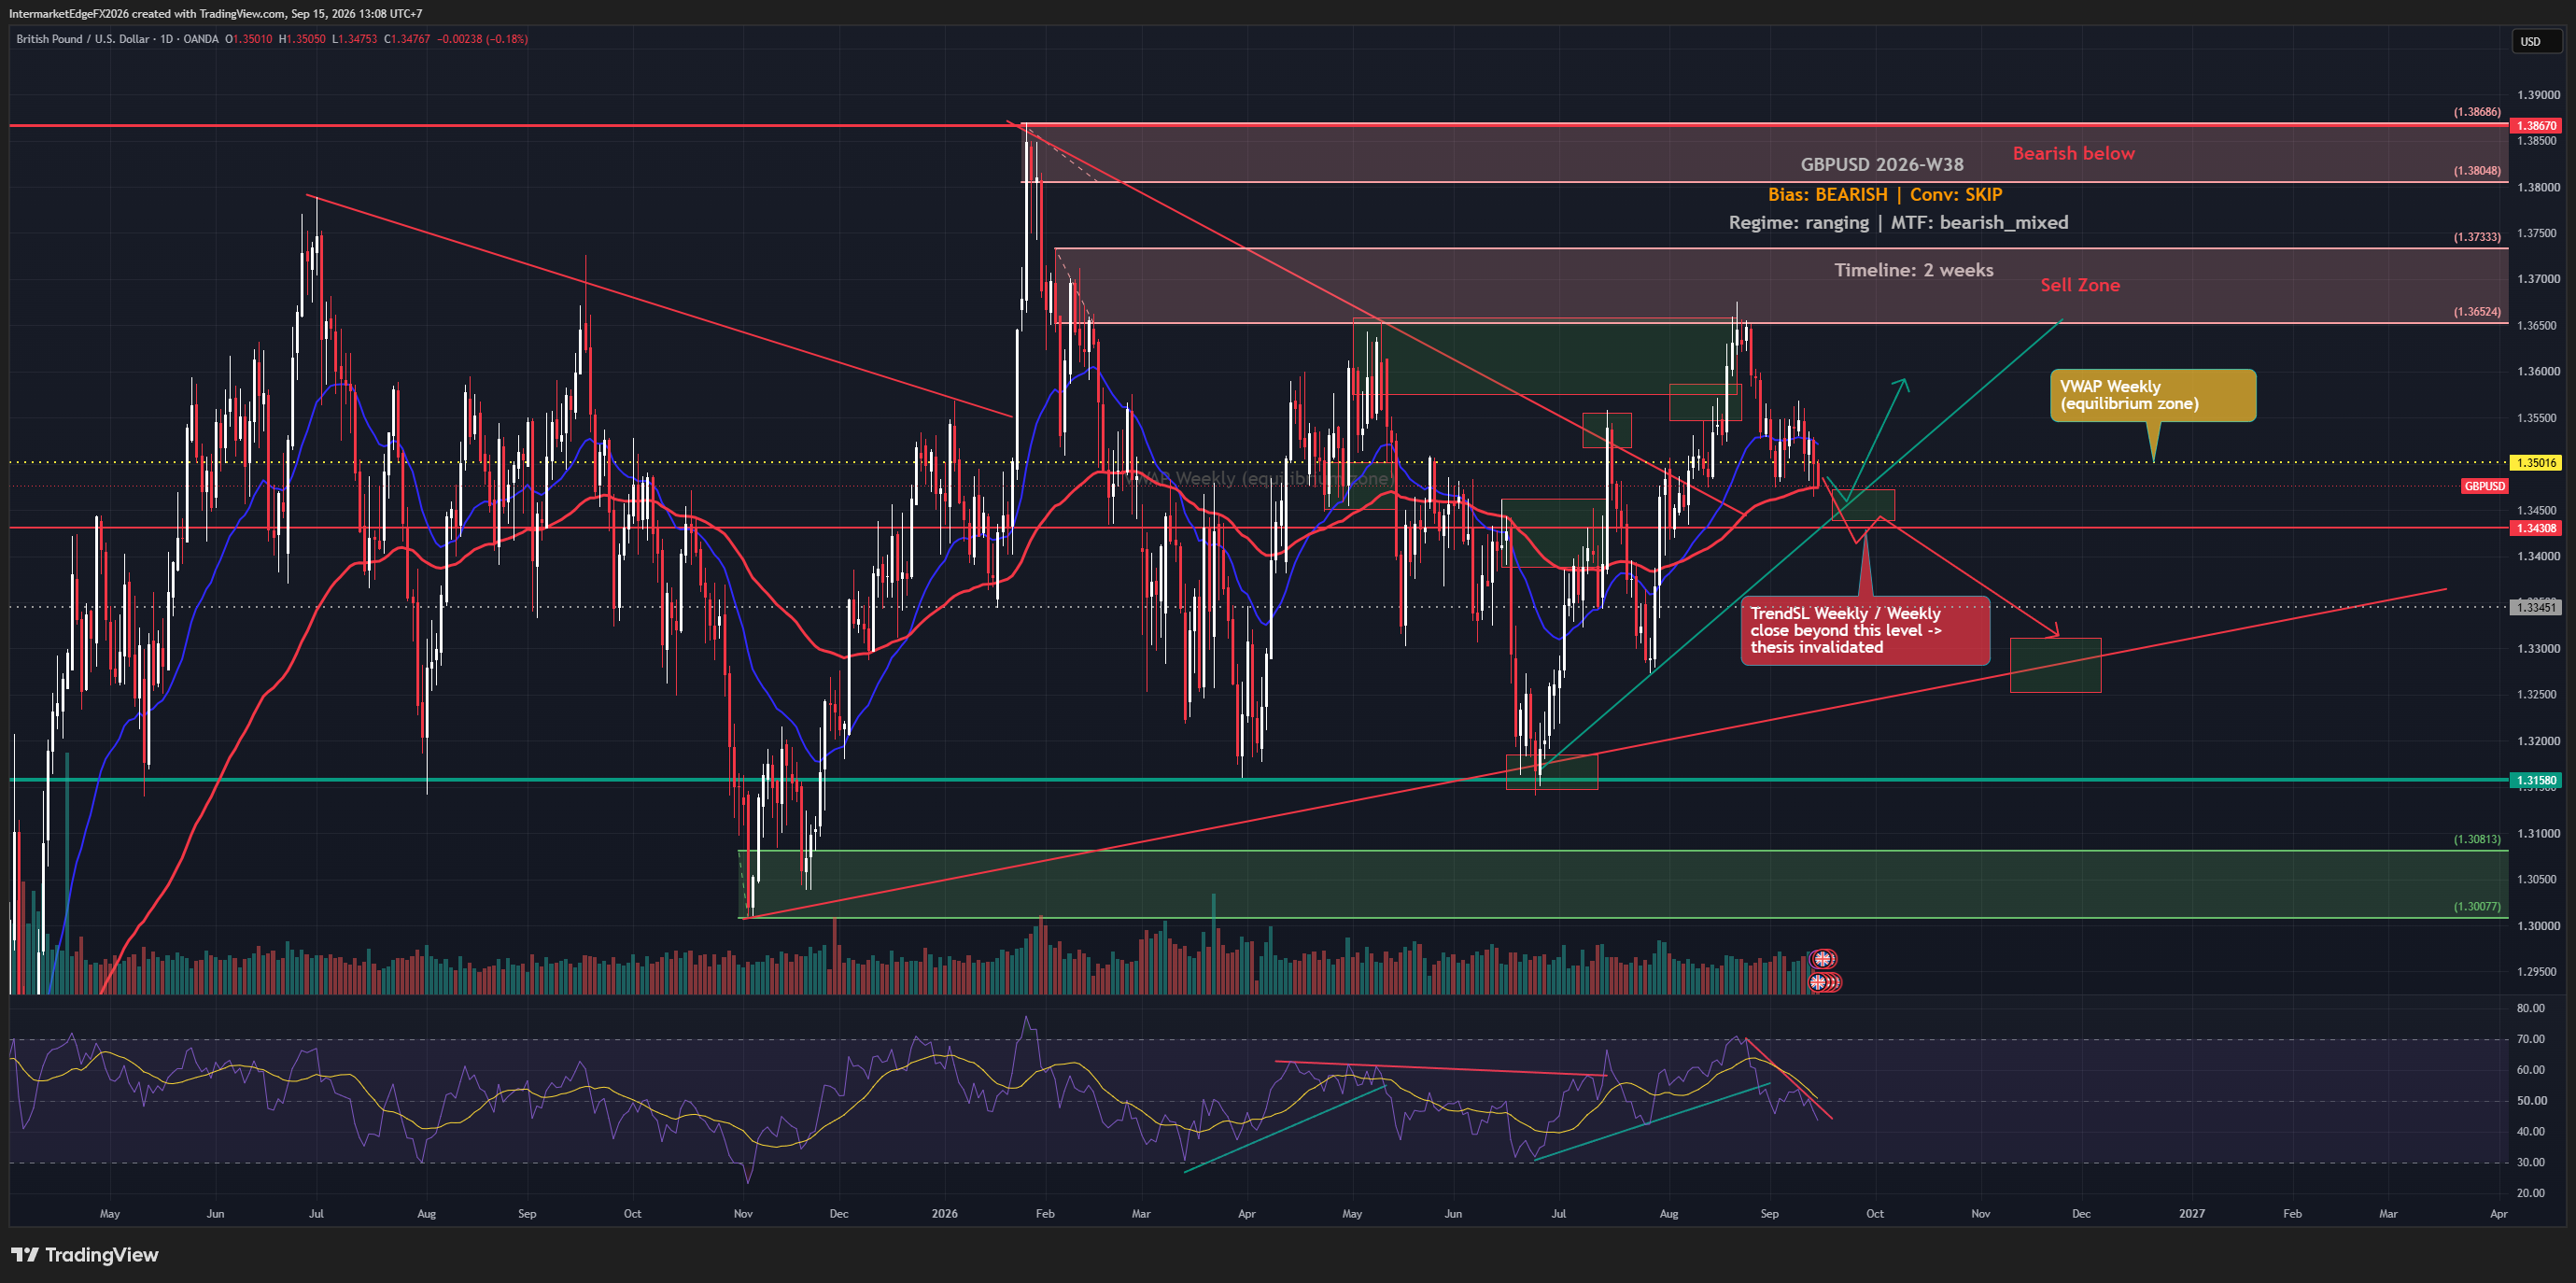
The US 10-year yield is pressing toward 5%, a level not seen since 2007, and that alone is enough to keep a bearish lean on GBPUSD for this week. But with the Federal Reserve decision due September 16 and the Bank of England following on September 17, the rate-differential story is incomplete. GBPUSD touched 1.3474 before recovering, and how it responds to those two decisions will matter far more than where it sits right now. The directional lean for GBPUSD this week is bearish, but the conviction behind that lean is deliberately thin, thin enough that staying out of a new position is the more defensible choice until the evidence consolidates. The entire bearish argument rests on one causal chain: a hawkish Fed stance pushes real yields higher, which widens the rate differential, the return gap between dollar and sterling assets, in the dollar's favor, making GBPUSD a structurally weaker pair. That chain is real and it is the clearest force in the setup. What is missing is any confirmation from price behavior or institutional positioning. COT data, which tracks how large speculative traders are aligned, contributes no directional score this week, meaning there is no evidence that professional money has built a meaningful short sterling position to amplify the macro thesis. Retail positioning at 54% long and 46% short, per broker sample data from fxssi on September 15, is effectively balanced and offers no contrarian signal in either direction. The TGA fell roughly 12% over four weeks to $843.7 billion as of September 9. A Treasury cash drawdown generally returns cash to the banking system, which can ease dollar funding conditions and work against the bullish dollar narrative at the margin. None of these cross-currents produce a clean picture. -- Intermarket Edge (Note: COT (Commitment of Traders) data is released weekly by the CFTC with a reporting-period lag -- it is not a real-time position feed. See cftc.gov for the exact release schedule.)

DXY Week W38-2026: Inflation Data Pushes Fed Hike Bets Higher, But the Dollar Sits Trapped Between Two Levels

DXY Week W38-2026: Inflation Data Pushes Fed Hike Bets Higher, But the Dollar Sits Trapped Between Two Levels

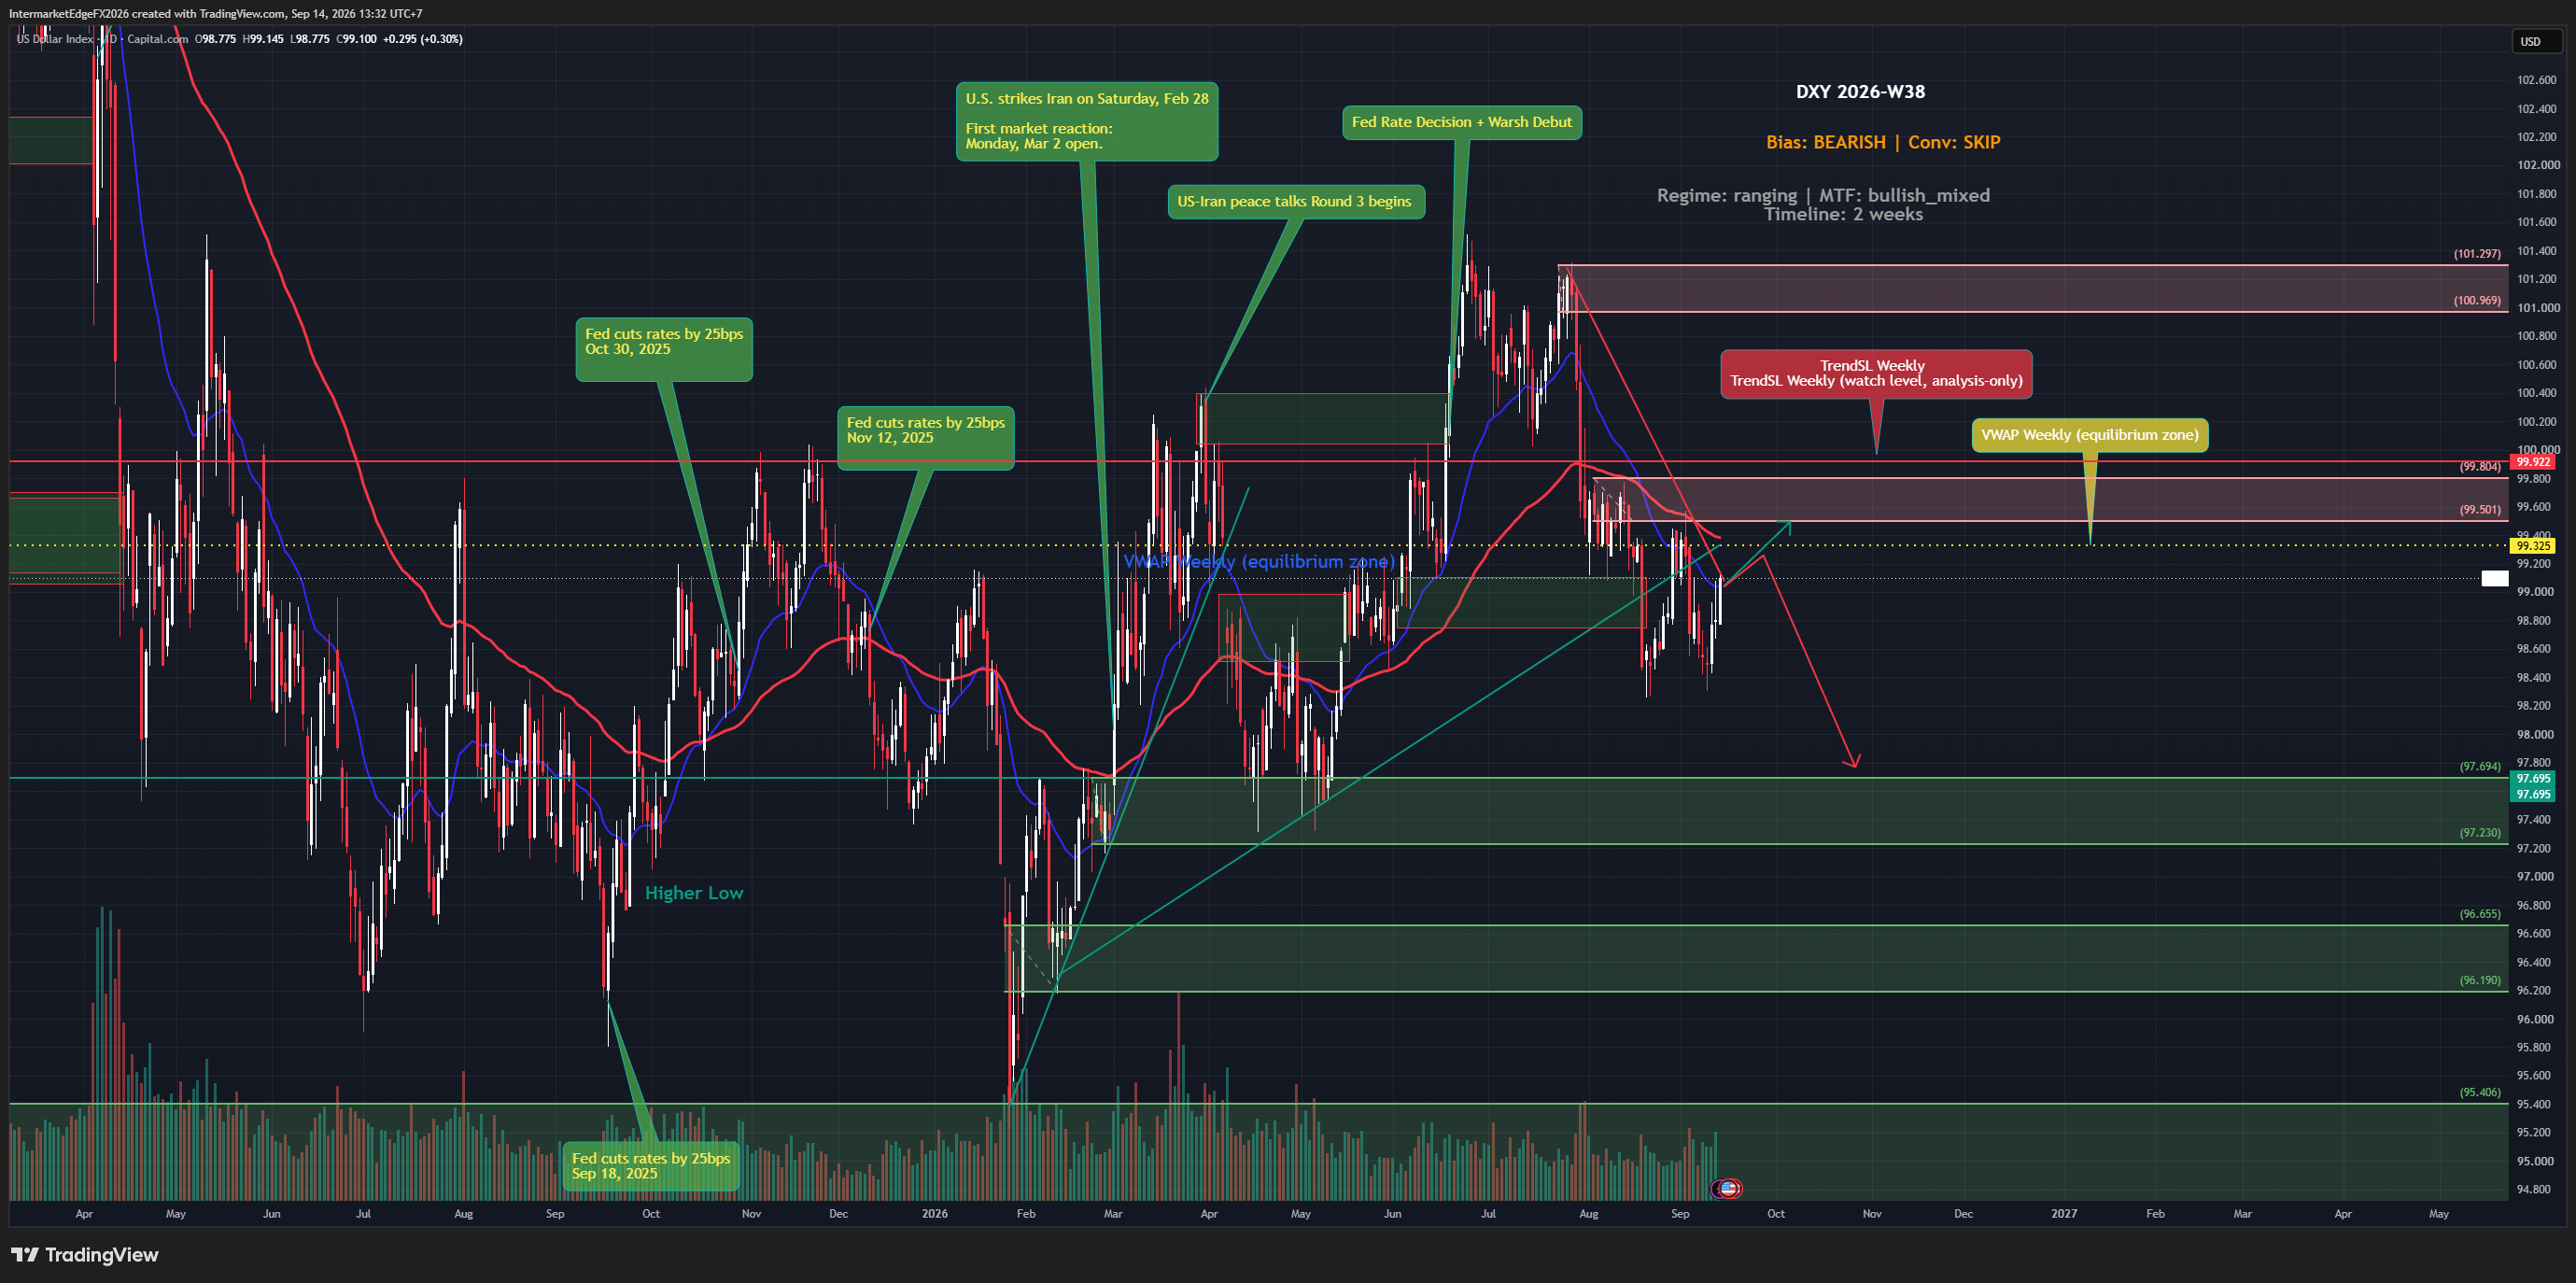
DXY is trading at 99.389 as of Monday, 14 September 2026 at 06:07 UTC. Price is above weekly VWAP at 99.325 and below weekly TrendSL at 99.922. Short-term momentum therefore runs against the bearish thesis, while the higher-time-frame bearish structure has not been invalidated. The macro picture is mixed ahead of the September 15-16 FOMC meeting. Inflation and a 2.55% US 10-year real yield support the dollar, but consumer sentiment at 47.8, rising inflation expectations and higher oil-shipping costs create a stagflationary policy problem. The US liquidity proxy increased by about $96.7 billion over four weeks, adding a modest structural headwind for USD. COT positioning points to stretched speculative dollar longs, although the brief lacks the exact report week and net-position figure. FXSSI retail positioning is balanced, with a derived DXY component reading near 53.5% long and 46.5% short. VIX and CNN Fear & Greed provide equity risk context rather than an FX signal. The weekly decision is to stand aside. A weekly close above TrendSL at 99.922 would invalidate the bearish framework. Price is already above VWAP, so sellers do not have short-term momentum confirmation. A sustained loss of VWAP support after FOMC would strengthen the bearish case. -- Intermarket Edge

DXY Week W37-2026: Strong Payrolls, but the Dollar Cannot Hold Its Gains

DXY Week W37-2026: Strong Payrolls, but the Dollar Cannot Hold Its Gains

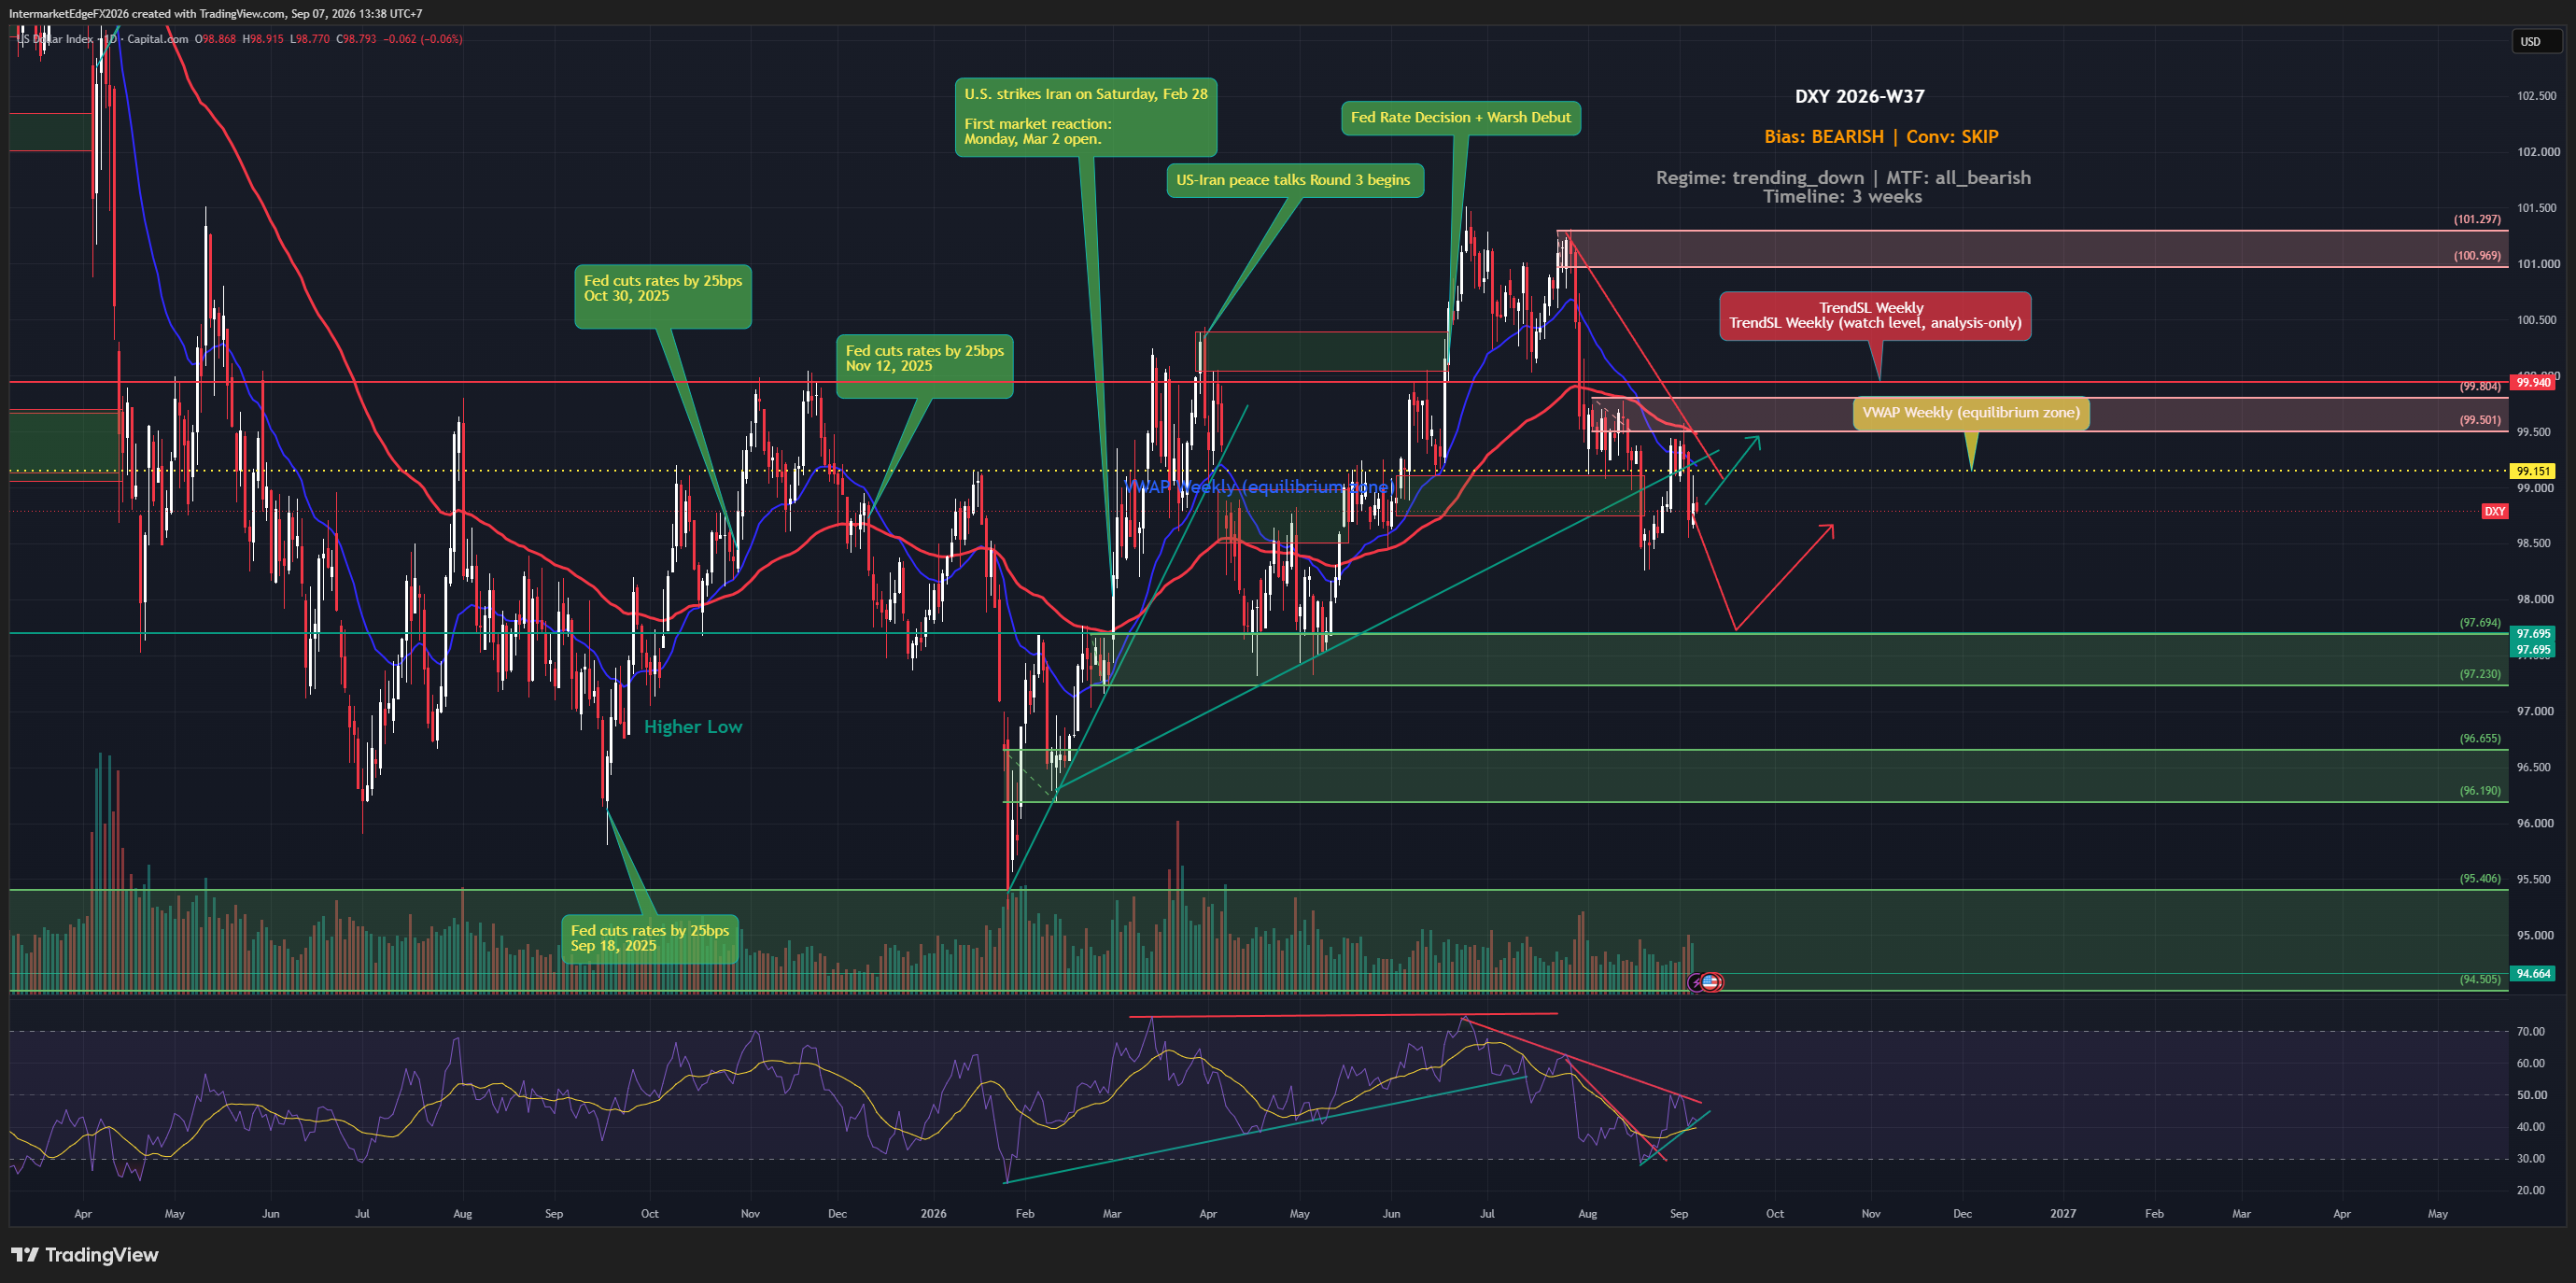
DXY Week W37-2026: strong payrolls, weak follow-through. August payrolls rose 162,000 against the Reuters consensus of 56,000, but the dollar pared its initial gains. Expectations of ECB and BOJ tightening can limit the relative US rate advantage; these remain expectations, not policy decisions. The locked quote is 99.165 at 03:58 UTC on Monday, September 7, 2026, from yfinance:DX-Y.NYB:1m. Price is ABOVE VWAP weekly at 99.151, testing from above by 0.014 points. That is an active short-term momentum conflict with the bearish view. Price remains BELOW TrendSL weekly at 99.94. The bias is bearish, the regime is a downtrend, and monitored timeframes are bearish. The horizon is three weeks. The action state is SKIP: stand aside. Neither the directional classification nor a later VWAP crossing is permission to enter a trade. A weekly close above TrendSL weekly at 99.94 would invalidate the bearish structure. This condition is pending; an intraday move would not be sufficient. August PPI is scheduled for September 10 and August CPI for September 11, both at 08:30 US Eastern / 19:30 Vietnam time, per ForexFactory calendar data. Outcomes are not yet known. For information and education only. Not financial advice.

DXY Weekly Outlook: A Bearish Trend Meets a Crowded Short

DXY Weekly Outlook: A Bearish Trend Meets a Crowded Short

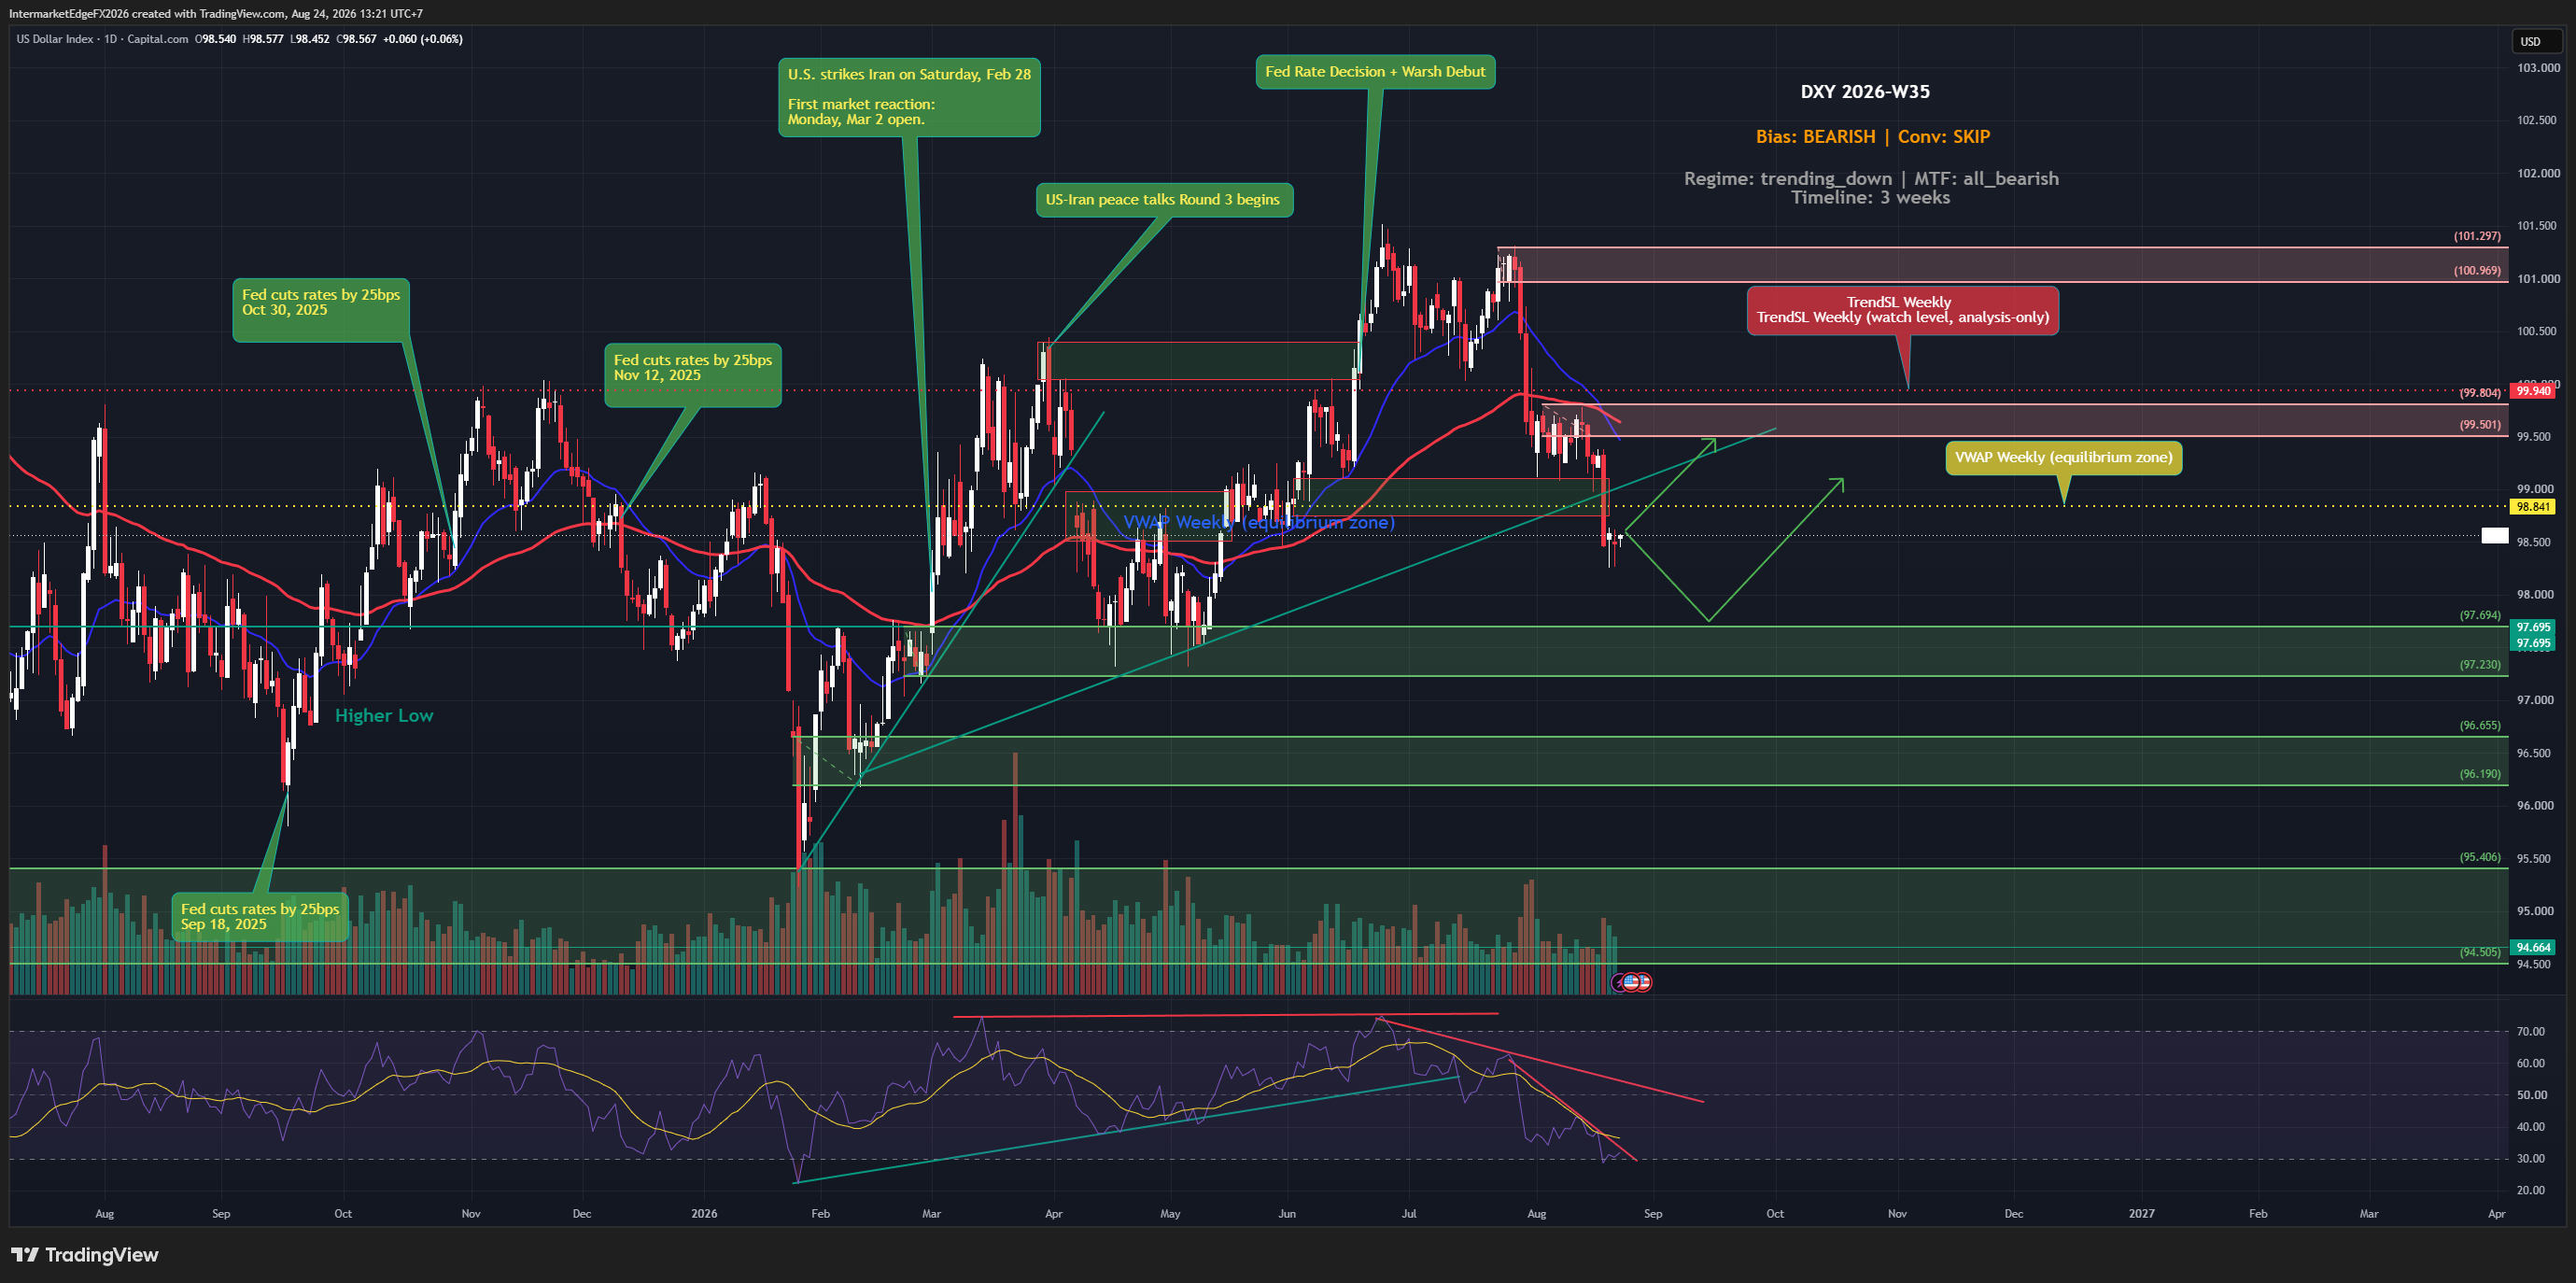
The US Dollar Index is trading near multi-month lows heading into Week W35-2026, and the bearish macro case looks clean on the surface, debt concerns, a weakening fiscal backdrop, and cross-timeframe alignment all pointing down. But underneath that surface, leveraged funds have already crowded into the short side, and price is actually testing from above the weekly VWAP at 98.841. When positioning is extreme and price refuses to break, the cleanest-looking trades tend to produce the messiest exits. The analytical framework carries a bearish bias on DXY for the three-week horizon, with the regime classified as trending down, meaning price structure, momentum, and multi-timeframe alignment are all oriented lower. In principle, the correct tactical posture in a trending-down regime is to follow the trend, not fade it. But the conviction here is deliberately set aside, and that deserves a clear explanation rather than a vague confidence label. Three signal sources are active this week: technical price action is actually leaning bullish, COT positioning is bearish, and macro defaults to a mild bullish tilt contingent on COT confirmation. The direct conflict between rising price action and extreme short positioning by leveraged funds, a COT divergence, is the central problem. COT divergence of this type, where price moves in one direction while professional speculators pile into the opposite side, carries two plausible readings: either the crowd is right and price is about to follow their positioning, or the crowd is too crowded and a short squeeze, a rapid, forced unwind of those short positions, is about to punish late entries. A short squeeze in this context means anyone short the dollar gets forced to cover simultaneously, driving the price sharply higher against the prevailing trend. -- Intermarket Edge (Note: COT (Commitment of Traders) data is released weekly by the CFTC with a reporting-period lag -- it is not a real-time position feed. See cftc.gov for the exac

DXY Week W34-2026: Retail Sales Shock Sends Dollar Testing 99.485 VWAP, But a Crowded Short Could Flip the Move

DXY Week W34-2026: Retail Sales Shock Sends Dollar Testing 99.485 VWAP, But a Crowded Short Could Flip the Move

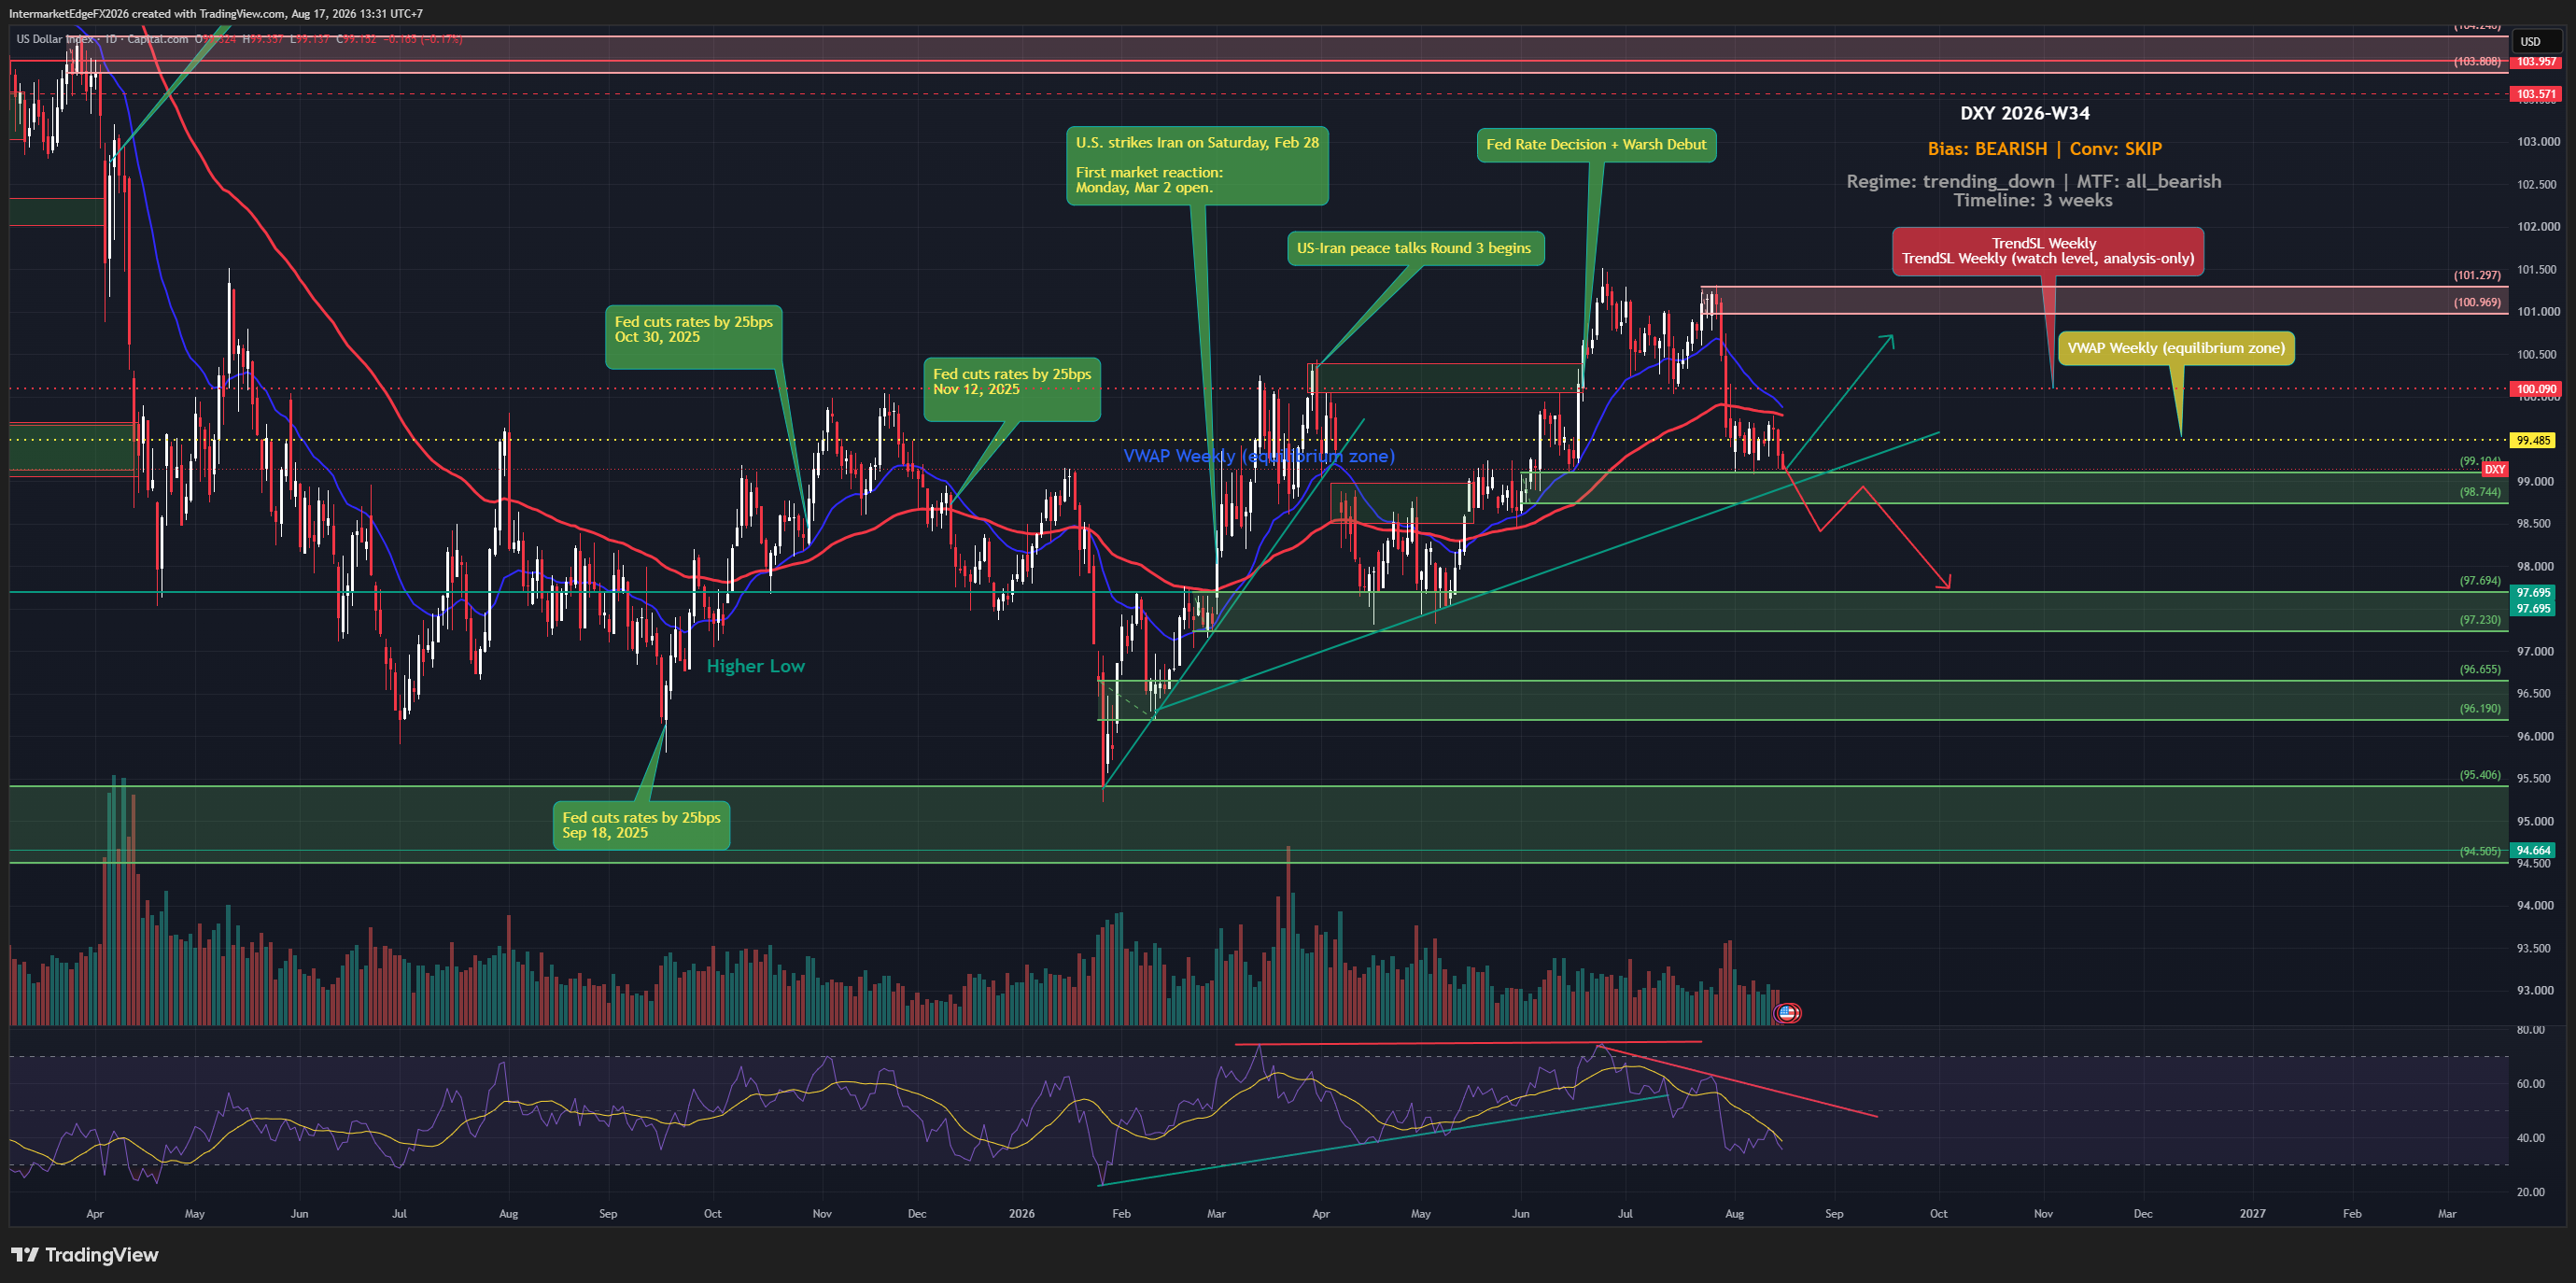
The dollar is under quiet but persistent pressure this week, with DXY trading at 99.479 as of Monday 17 August 2026, just a fraction below its weekly VWAP at 99.485, testing from underneath. A surprise drop in US retail sales, a consumer sentiment index that collapsed to 51.0 against a 54.2 expectation, and a core CPI print of 0.0% against a 0.2% forecast have combined to erode the fundamental case for a stronger dollar, even as yields stay elevated. The direction leans bearish, but the evidence is not yet convincing enough to size a position. The overall lean for DXY this week is bearish, and the trend regime is clearly downward, but the conviction supporting that bias is deliberately low, and the analysis here reflects a decision to stand aside rather than treat the bearish lean as an actionable entry signal. Here is why that matters: the framework shows a direct conflict between what price has been doing and what institutional positioning implies. Price action has been constructive, technically, the trend has shown some bullish characteristics. But commitments of traders data shows leveraged funds sitting at extreme short positioning. That divergence creates what traders call crowding risk on the short side: if the majority of active participants are already short (note, the COT figures cited here reflect directional scoring from the brief and do not specify the exact report week or net-position count, so treat this as directional evidence rather than a standalone citable statistic), there are fewer fresh sellers left to push the dollar lower, and any positive catalyst can trigger a sharp short-covering rally that has nothing to do with fundamentals changing. -- Intermarket Edge

DXY Week W33-2026: Dollar Tests VWAP From Underneath as Fed Hawk Dissent and Iran Uncertainty Pull in Opposite Directions

DXY Week W33-2026: Dollar Tests VWAP From Underneath as Fed Hawk Dissent and Iran Uncertainty Pull in Opposite Directions

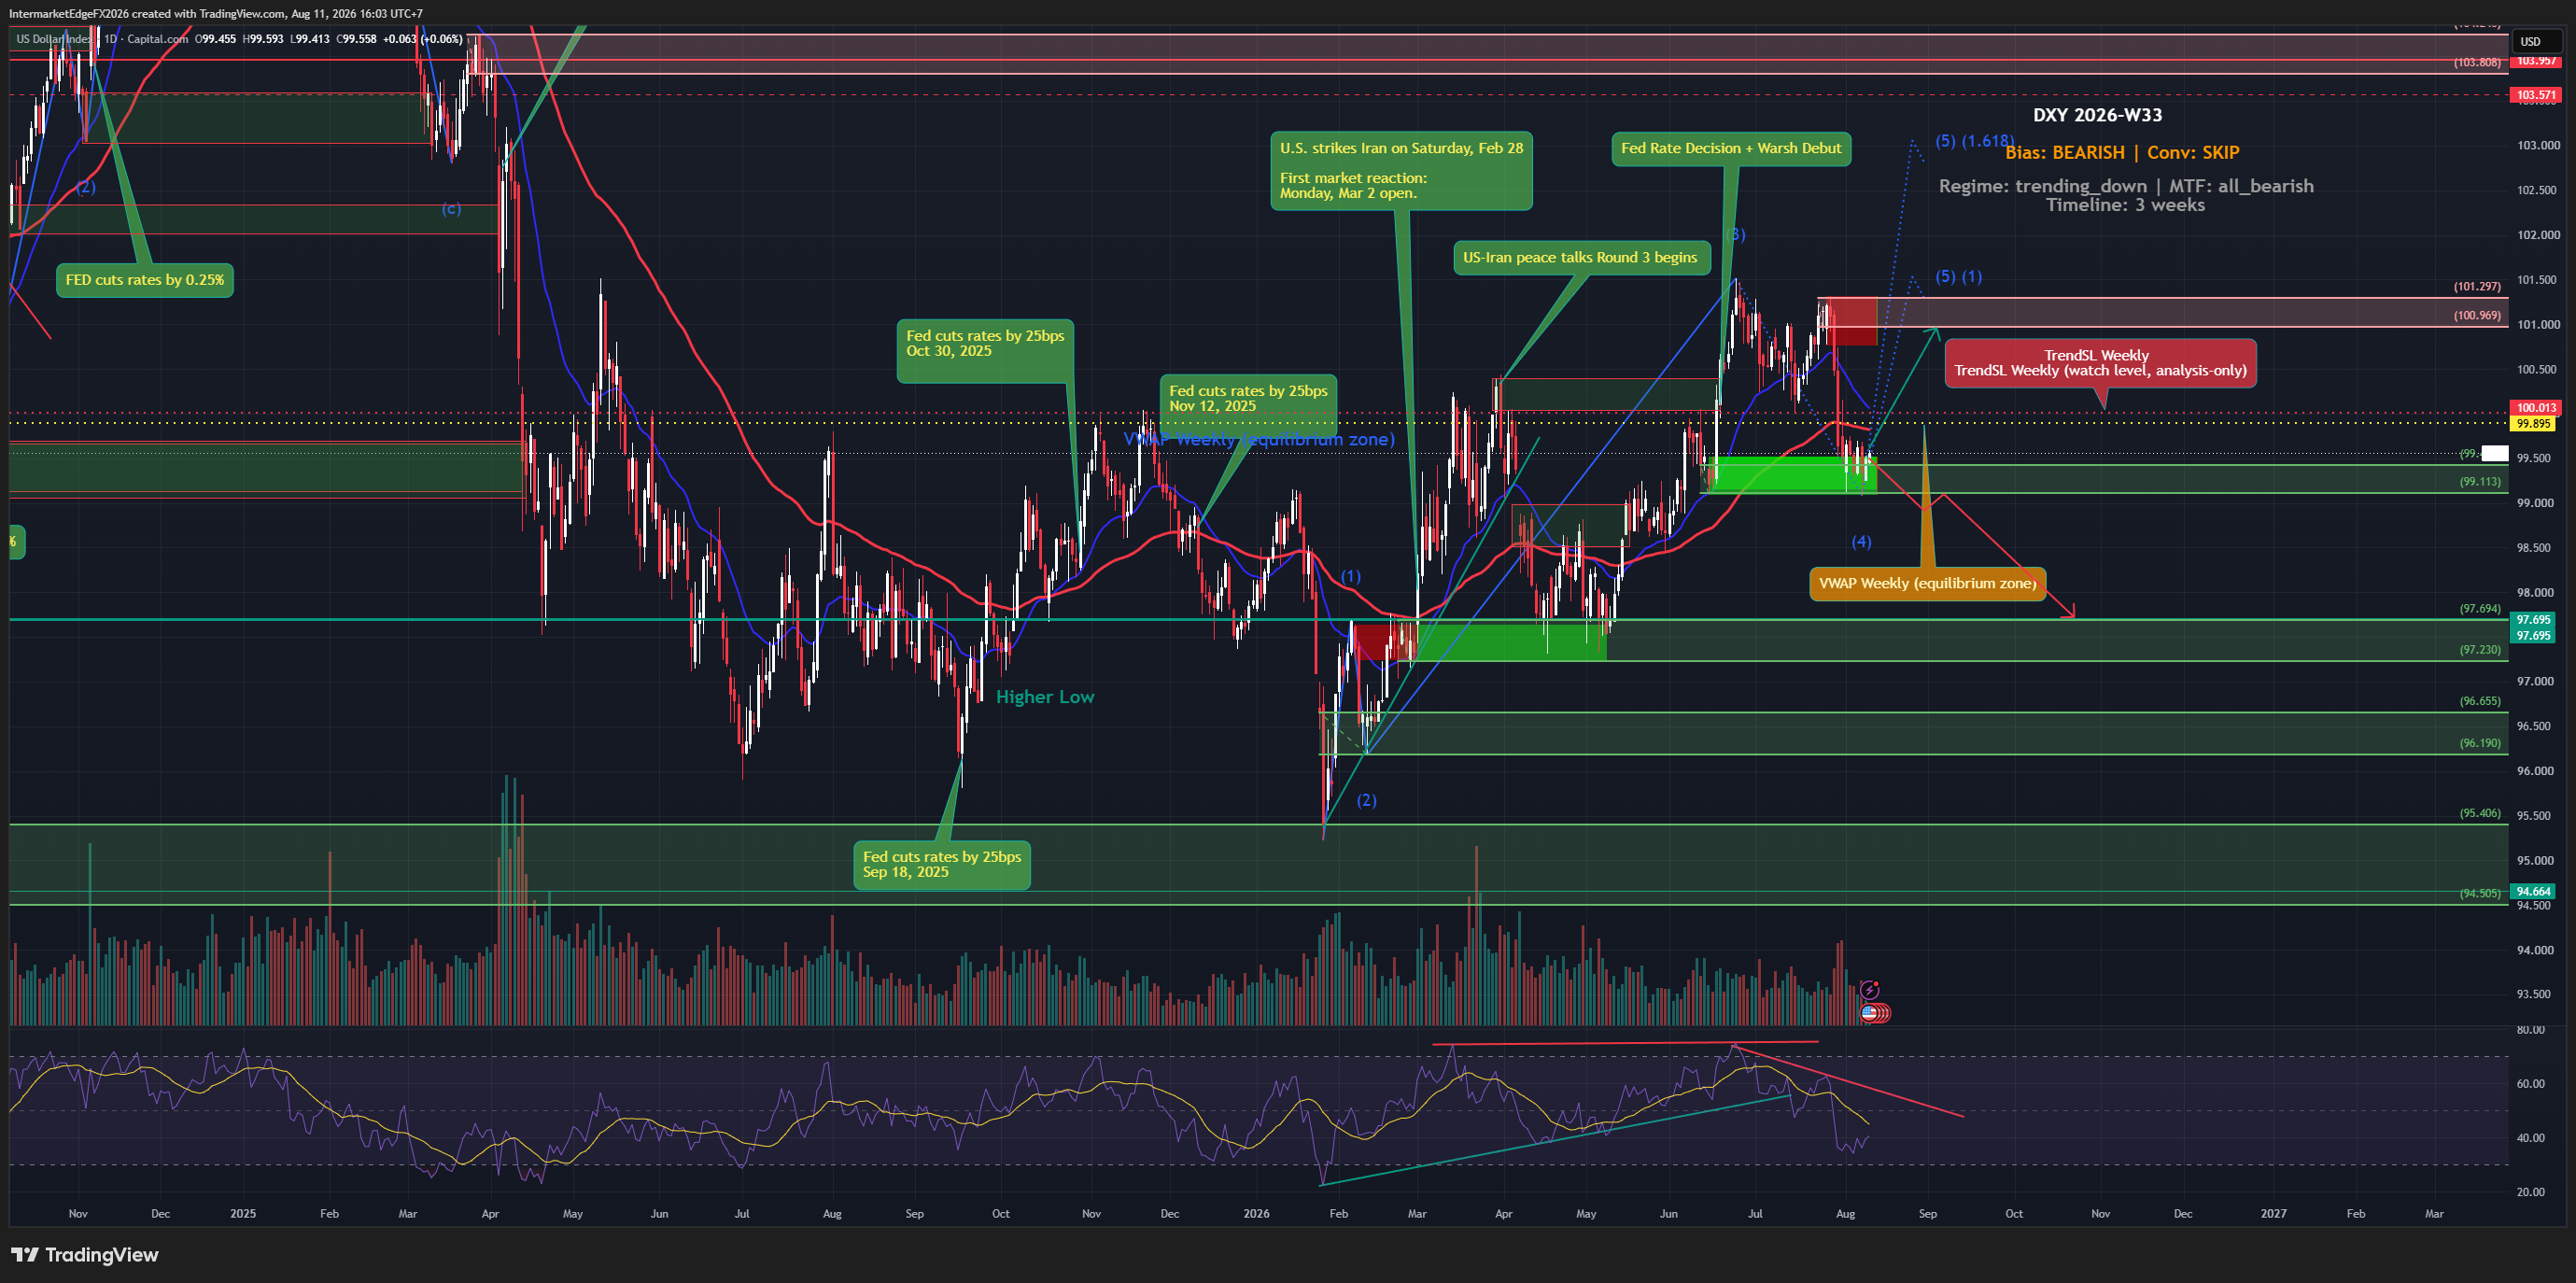
The US Dollar Index slipped to 99.846 as of Tuesday, 11 August 2026 at 08:40 UTC, sitting below its weekly VWAP of 99.895 and testing that level from underneath. A shocking Core CPI miss, actual 0.0% against a 0.2% forecast, has stripped one of the dollar's key near-term supports, even as Fed dissenter Hammack openly advocates for rate hikes and geopolitical noise from the Iran situation keeps traders cautious. The multi-timeframe picture is uniformly bearish, but conviction is too thin to size aggressively in either direction right now. The overall bias on DXY for W33-2026 is bearish, aligned with a confirmed trending-down regime, and every timeframe in the multi-timeframe stack is pointing in the same direction. In that sense, the directional read is not ambiguous, the regime says trend-follow short. The problem is conviction, which is assessed as skip-level, meaning this is explicitly not a week to be sizing into fresh positions aggressively, and the reasons for that are worth spelling out clearly so traders understand the risk they are taking if they choose to engage anyway. The central tension is a direct conflict between price action and Commitments of Traders (COT) positioning data. Price action over recent sessions has been constructive for the dollar, carrying a bullish short-term signal, while COT data, which tracks reported positioning across speculator categories and should be read as directional evidence rather than a precise, citable statistic given the brief does not specify the exact report week or net-position figures, shows leveraged funds at extreme short positioning. This is a classic COT divergence setup, and the rule here is contrarian: when speculative shorts are already crowded to an extreme, the pool of fresh sellers willing to push price lower is by definition shrinking. -- Intermarket Edge

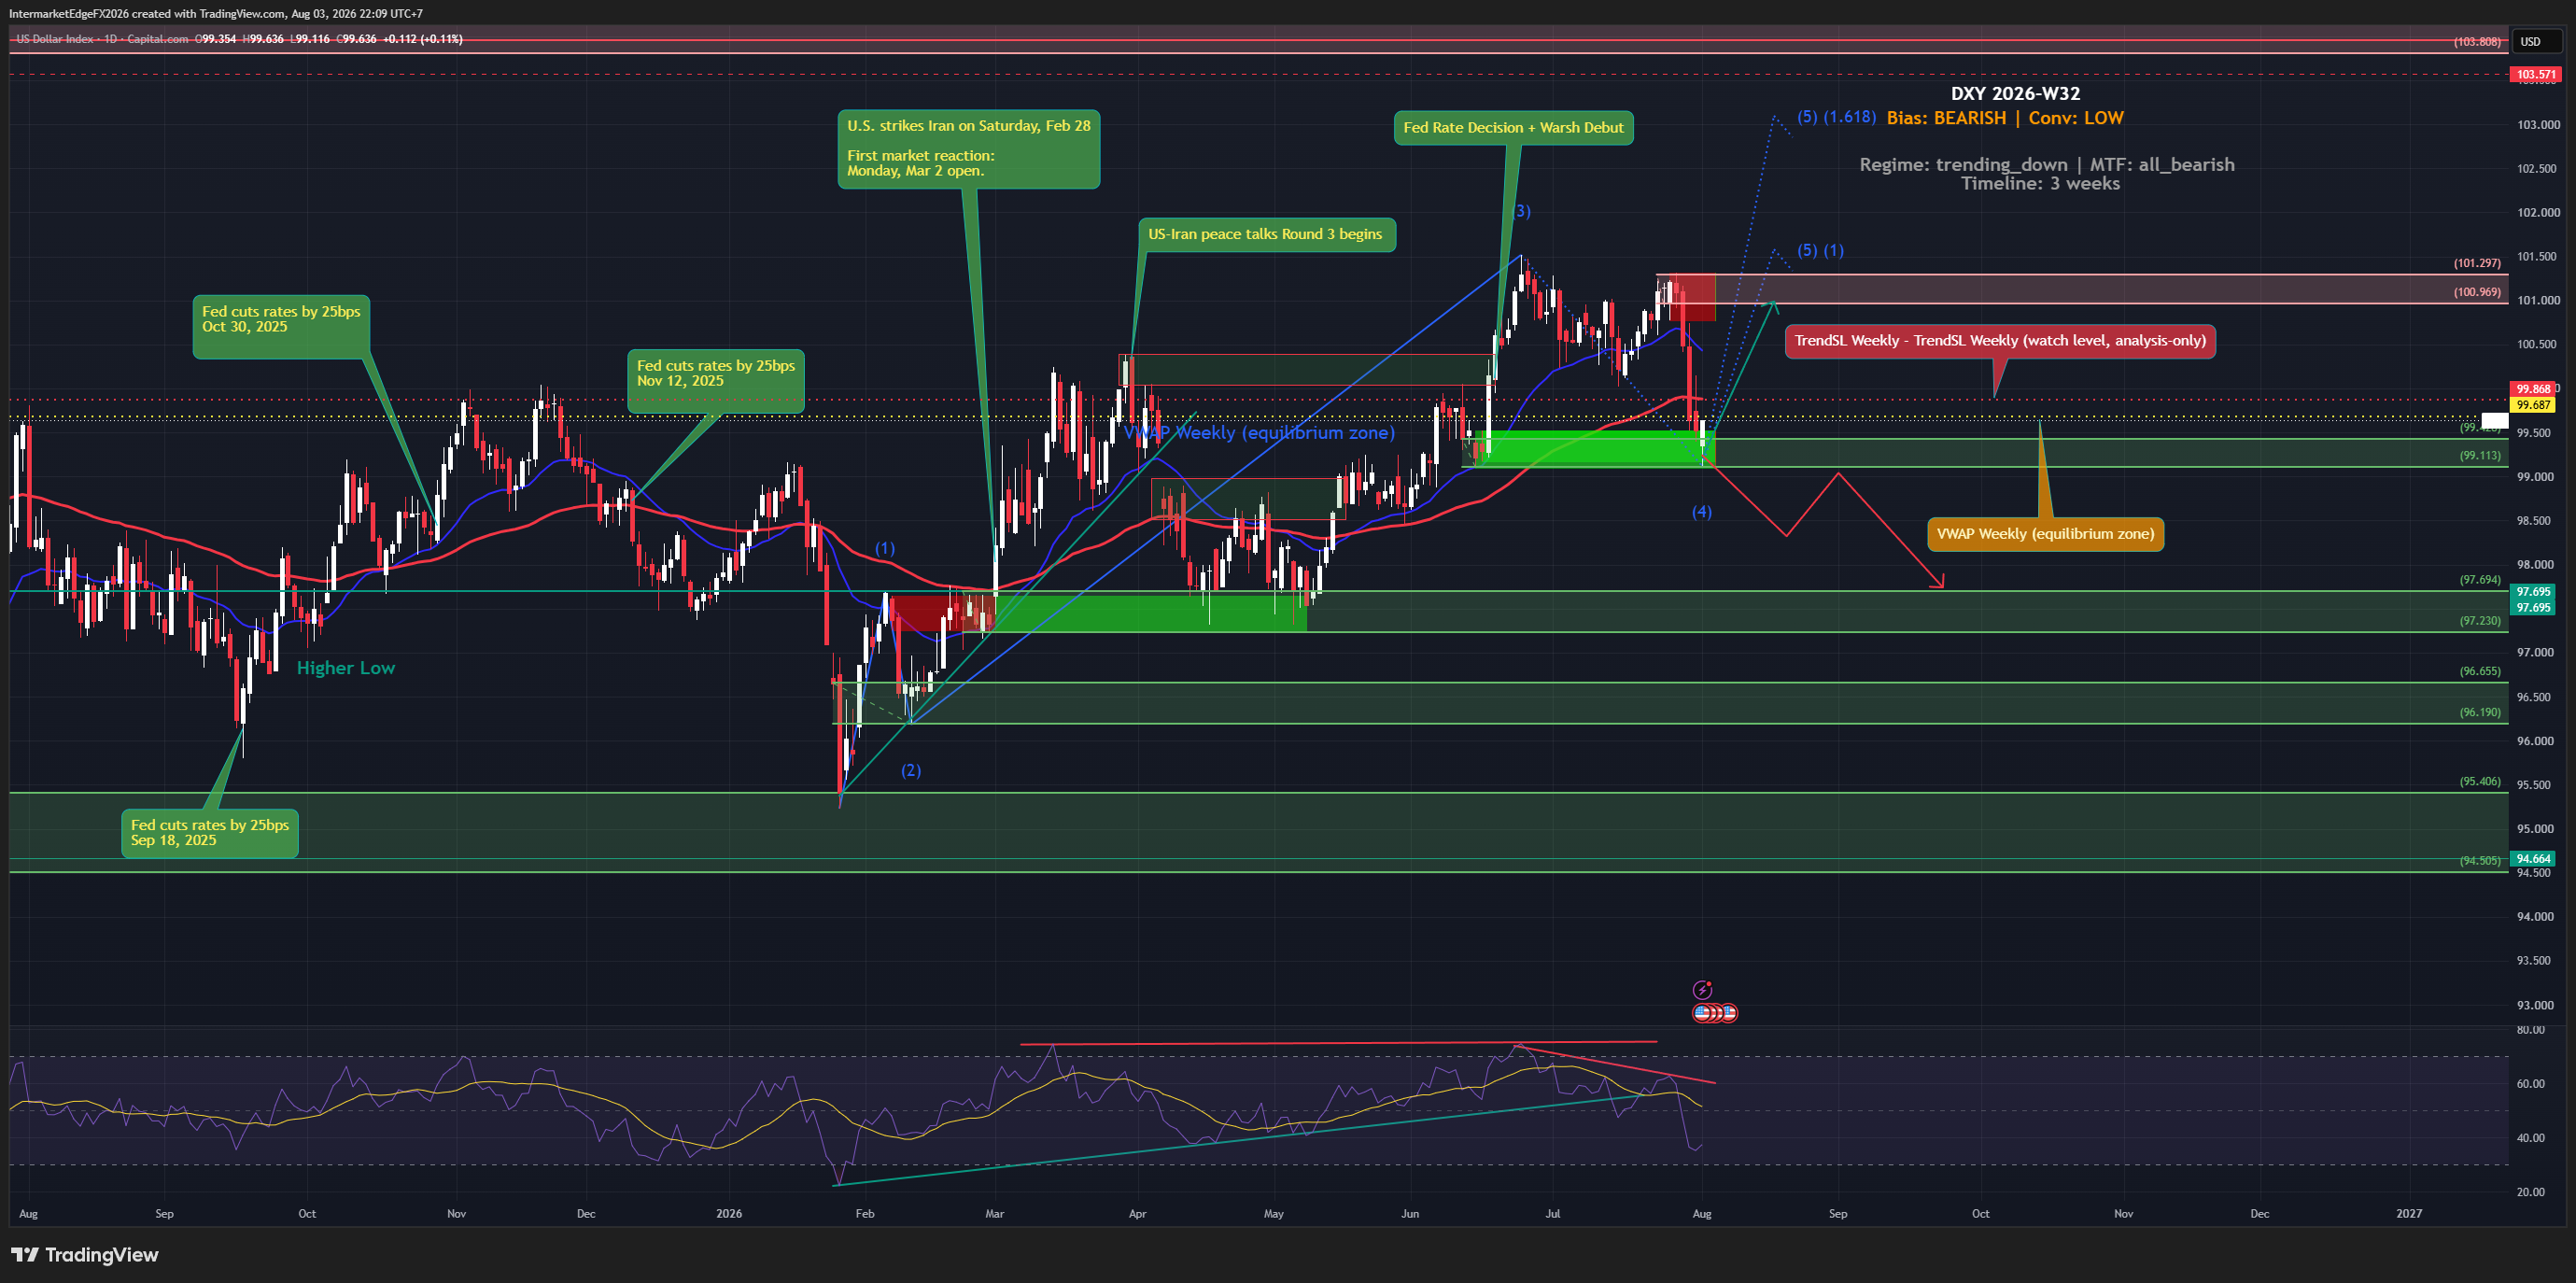
DXY Week W32-2026: ISM Manufacturing Surges to 55.6 as Dollar Tests VWAP at 99.687 From Above, But Macro Signal Conflict Keeps Bears Cautious

DXY Week W32-2026: ISM Manufacturing Surges to 55.6 as Dollar Tests VWAP at 99.687 From Above, But Macro Signal Conflict Keeps Bears Cautious

The US Dollar Index is under a trending bearish regime heading into Week W32-2026, yet the setup is anything but clean. Manufacturing activity just printed its strongest reading since May 2022, core CPI missed forecasts badly, and price is currently pressing against a critical structural level, all while the overall bias remains bearish with low conviction. This is a week for watching and assessing, not for forcing a position. The overall bias on DXY for Week W32-2026 is bearish, but conviction is explicitly low, and traders must handle this carefully. The multi-timeframe technical regime is aligned bearish across all timeframes, and the broader trend regime is classified as trending down with moderate confidence. That said, the signal picture is heavily conflicted. Both price action and the macro backdrop are currently pointing toward Dollar strength, the ISM beat, the still-elevated real yield of 2.41%, and the active causal chains around Fed policy relative to the G6 central bank basket and the residual influence of the prior hot inflation environment all argue for USD resilience. The rule engine's bearish override is driven by Fed policy divergence assessed relative to the broader G6 central bank basket, not by any single domestic data point, and it represents a structural thesis rather than a tactical one. Critically, three of five signal input categories, positioning data, liquidity indicators, and sentiment surveys, fired zero confirming signals this week. That is not a minor gap; it means the bearish call is resting on a much narrower evidential base than would normally justify an active directional stance. A macro bullish signal is also present but flagged as a provisional placeholder, subject to override if positioning data aligns in future reports. -- Intermarket Edge

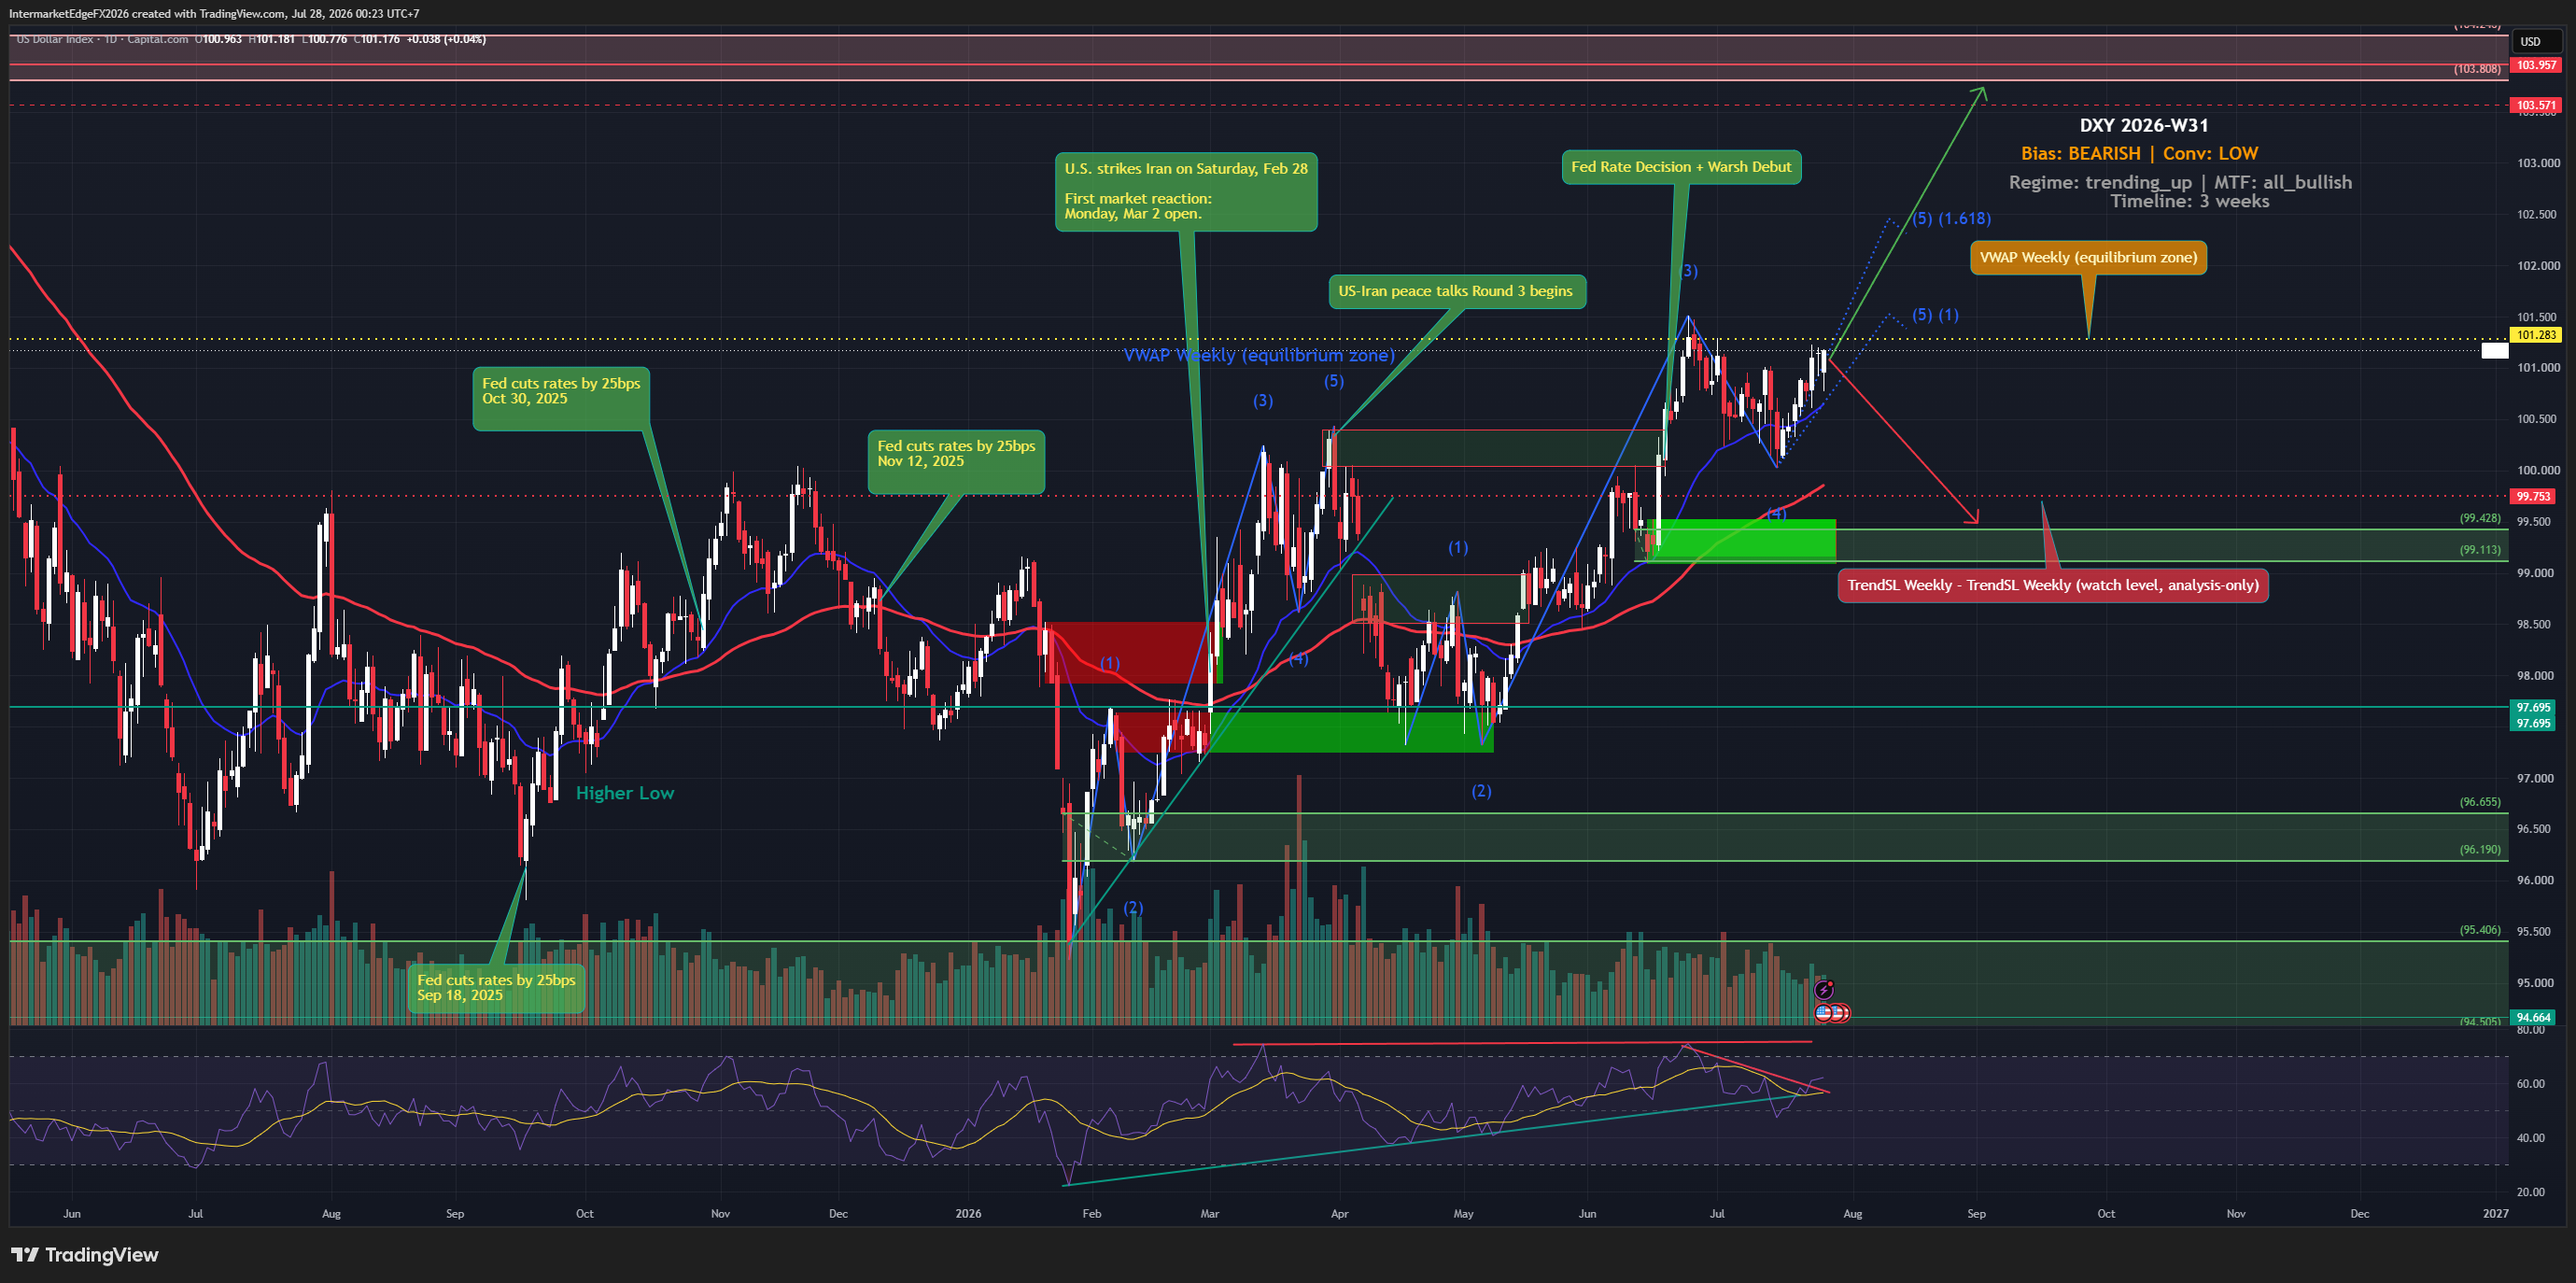
DXY Week W31-2026: Price Holds Above VWAP at 101.283 as Technicals and Macro Both Turn Bullish, Yet the Rule Engine Stays Bearish

DXY Week W31-2026: Price Holds Above VWAP at 101.283 as Technicals and Macro Both Turn Bullish, Yet the Rule Engine Stays Bearish

As of Monday, 27 July 2026 at 16:14 UTC (yfinance near-realtime), DXY trades at 101.46 — above weekly VWAP 101.283 by 0.18 points, testing from above, and well above TrendSL weekly 99.753 by 1.71 points. Both break conditions remain unmet: bearish structure is not invalidated. The core problem this week is a hard signal conflict. The rule engine outputs a bearish bias, but nearly every underlying input disagrees. Daily, Weekly, and Monthly TrendSL are all bullish — the strongest technical alignment available. Two active macro causal chains (Fed hawkishness and hot CPI) both carry high USD-bullish weights. Price action is bullish. The bearish label stems from a default Fed-vs-G6 rate differential assumption applied in the absence of COT confirmation; it carries low conviction. COT, liquidity, and sentiment sources fired no rules, so the bearish case has no positioning support. Treat the bias label as a placeholder, not a directional call. Yield structure adds complexity: US 10Y at 4.71%, 2Y at 4.37% — a positive term spread — with real 10Y yield at 2.43%, still supportive of USD carry. No carry unwind signal is present. Key risk event: per ForexFactory calendar data, FOMC rate decision, statement, and press conference are all scheduled for 29 July 2026; Advance GDP and Core PCE follow on 30 July 2026. These dates are from a secondary aggregator, not official Federal Reserve confirmation. Crowding risk around the FOMC is real — a dovish surprise could resolve the signal conflict bearishly; a hold-with-hawkish-tone outcome reinforces the technical bullish case. Bottom line: signals are genuinely conflicting. Do not lean into the bearish label without COT confirmation. Watch the 29–30 July data window. -- Intermarket Edge

Stay in the loop

Get notified about new research, macro insights, and market analysis.

InterMarketEdge

© 2026 InterMarketEdge. Financial intelligence for inter-market traders.